Step-Up SIP kya hai, kaise kaam karta hai aur kab choose karein, real ₹ examples ke saath.
- ₹5,000Year 1
- ₹5,500Year 2
- ₹6,050Year 3
- ₹6,655Year 4
- ₹7,321Year 5
Illustration: 10% annual step-up
Step-Up SIP samajhne ke liye ek simple situation dekhte hain. Aapne ₹40,000 salary ke time ₹5,000 ki SIP start ki. Kuch saal baad salary ₹60,000 ho gayi, lekin SIP abhi bhi ₹5,000 hi hai. Habit bani rahi, par contribution income ke saath nahi badha.
Ab sawal yeh hai: kya SIP contribution bhi income ke saath gradually increase ho sakta hai? Is guide mein dekhenge ki yeh idea kya hai, regular SIP se kaise alag hai, numbers mein kaisa dikhta hai, aur kab choose ya reconsider karna theek hai. Saare examples hypothetical hain; returns guaranteed nahi hote.
Step-Up SIP Kya Hai?
SIP (Systematic Investment Plan) mein aap mutual fund mein regular interval par, usually monthly, ek fixed amount invest karte ho. Regular SIP mein yeh amount aam taur par tab tak same rehta hai jab tak aap khud change na karo.
Step-Up SIP (jise top-up SIP bhi kehte hain) mein aap contribution ko pre-decided schedule par badhate ho. Increase do tarah ka ho sakta hai: fixed percentage (jaise har saal 10%) ya fixed amount (jaise har saal ₹1,000).
Dhyan rahe: SIP apne aap nahi badhti. Increase tabhi hota hai jab aap step-up option select karte ho, aur exact process platform ya AMC ke hisaab se alag ho sakti hai.
Regular SIP vs Step-Up SIP: Kya Difference Hai?
| Feature | Regular SIP | Step-Up |
|---|---|---|
| Initial contribution | Fixed | Fixed initially |
| Contribution over time | Usually same, jab tak aap change na karo | Planned increase over time |
| Income growth alignment | Limited, unless manually changed | Planned increases ke liye better suited |
| Complexity | Simple | Thoda zyada structured |
| Suitable for | Fixed contribution chahne wale | Income ya cash-flow growth expect karne wale |
Step-Up hamesha better hota hai, aisa kehna sahi nahi hoga. Suitability aapki income, expenses, goals, time horizon, cash-flow stability aur risk tolerance par depend karti hai.
REGULAR SIP
- ₹5,000Year 1
- ₹5,000Year 2
- ₹5,000Year 3
- ₹5,000Year 4
STEP-UP SIP
- ₹5,000Year 1
- ₹5,500Year 2
- ₹6,050Year 3
- ₹6,655Year 4
Illustration based on a 10% annual increase (monthly SIP amount)
Step-Up SIP Kaise Kaam Karta Hai?
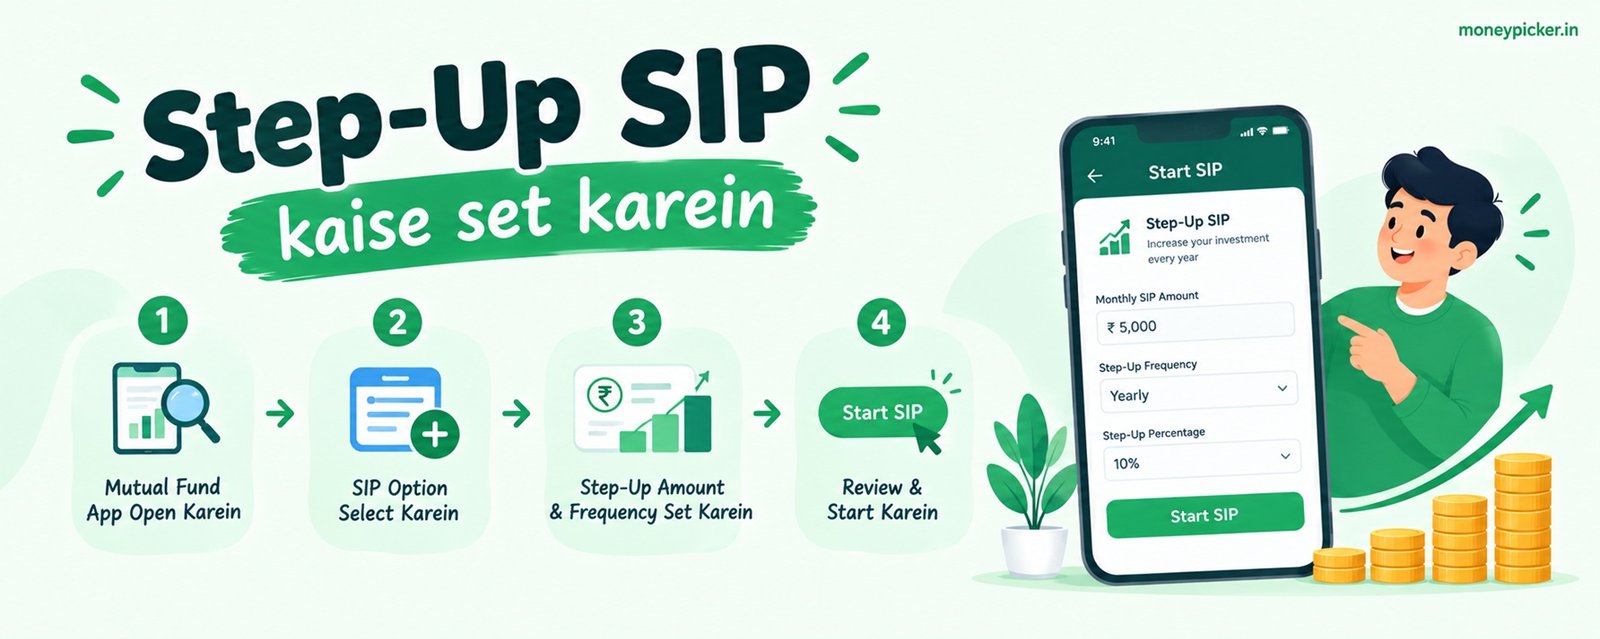
- Initial SIP amount choose karo, jaise ₹5,000/month.
- Increase ka tareeka choose karo: percentage ya fixed amount.
- Timing set karo: increase kitne time baad hoga, jitna platform allow kare (commonly yearly).
- Contribution badhta hai aapke chosen instruction ke hisaab se.
- Invest karte raho aur plan ko time-to-time review karo.
Exact mechanics platform, AMC aur bank mandate setup ke hisaab se alag ho sakte hain, isliye terms pehle verify karein. Mutual fund basics ke liye AMFI ki official website reliable starting point hai.
Percentage Step-Up vs Fixed-Amount Step-Up
10% har saal (example)
Year 1: ₹5,000
Year 2: ₹5,500
Year 3: ₹6,050
Year 4: ₹6,655
₹1,000 har saal (example)
Year 1: ₹5,000
Year 2: ₹6,000
Year 3: ₹7,000
Year 4: ₹8,000
Percentage step-up current SIP par calculate hota hai, isliye rupee increase har saal thoda badhta hai (₹500, ₹550, ₹605). Fixed-amount step-up mein har baar same rupee amount add hota hai.
Step-Up SIP Example aur Calculation
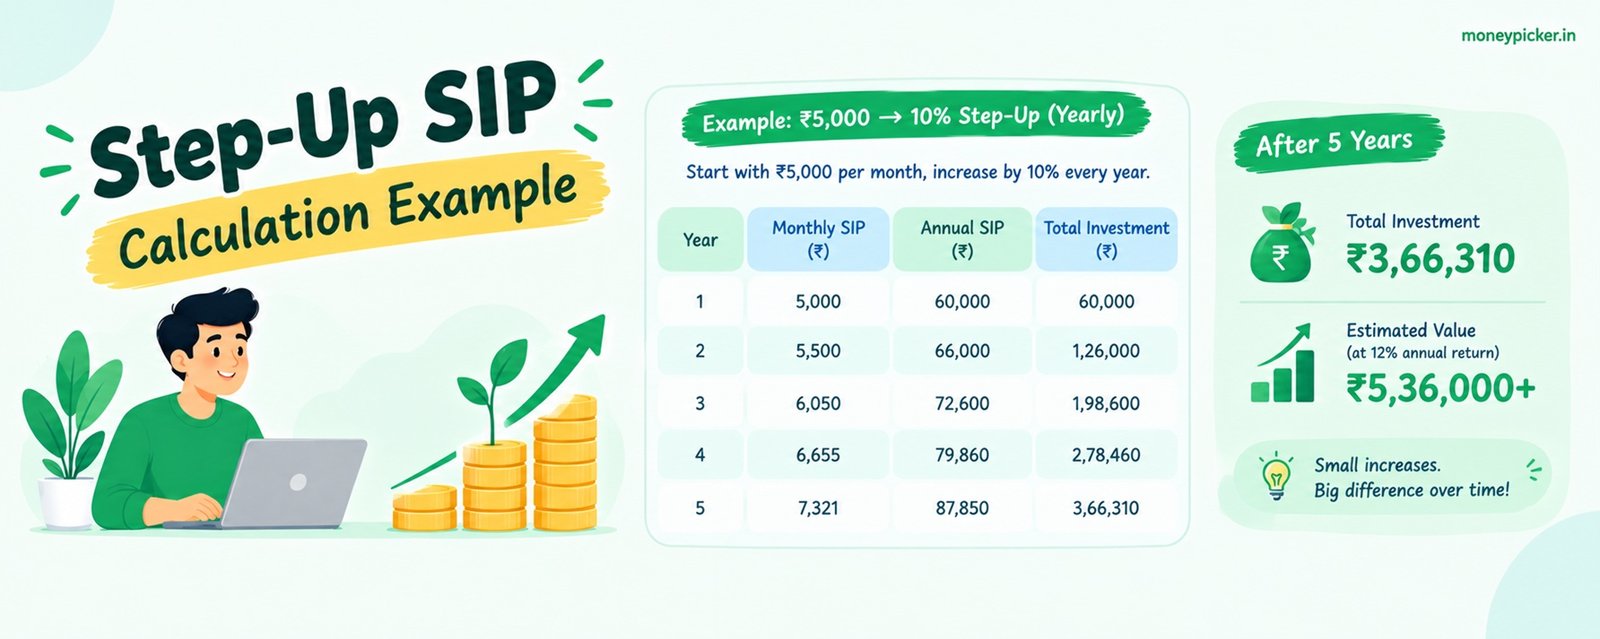
Hypothetical assumptions: initial SIP ₹5,000/month, annual step-up 10%, period 10 saal. Pehle 5 saal ka growth path:
Illustration: 10% annual Step-Up
| Year | Monthly SIP | Annual contribution |
|---|---|---|
| 1 | ₹5,000 | ₹60,000 |
| 2 | ₹5,500 | ₹66,000 |
| 3 | ₹6,050 | ₹72,600 |
| 4 | ₹6,655 | ₹79,860 |
| 5 | ₹7,321 | ₹87,846 |
| 6 | ₹8,053 | ₹96,631 |
| 7 | ₹8,858 | ₹1,06,294 |
| 8 | ₹9,744 | ₹1,16,923 |
| 9 | ₹10,718 | ₹1,28,615 |
| 10 | ₹11,790 | ₹1,41,477 |
| Total contribution (approx.) | ₹9.56 lakh | |
Step-Up SIP Calculation Ka Basic Logic
- Initial SIP₹5,000/month
- Annual increase10%
- Duration10 saal
- Assumed return10% p.a. (illustrative)
- Estimated future valueguaranteed nahi
Calculation monthly compounding par based hai. Result sirf estimate hai; actual market-linked value materially alag ho sakti hai.
Regular vs Step-Up: Projection
Same ₹5,000 start, 10 saal aur same 10% illustrative return ke saath dono scenarios:
Amount investedEstimated gains (illustrative)
| Scenario | Invested | Est. gains | Est. value |
|---|---|---|---|
| Regular SIP | ₹6.00 lakh | ₹4.24 lakh | ₹10.24 lakh |
| Step-Up (10%) | ₹9.56 lakh | ₹5.54 lakh | ₹15.10 lakh |
Actual returns market par depend karte hain aur negative bhi ho sakte hain. 10% illustrative assumption hai, forecast nahi. Regular SIP scenario check karna ho toh MoneyPicker SIP Calculator use kar sakte ho.
REGULAR SIP
- Same monthly contribution
- Lower total contribution
STEP-UP
- Contribution increases
- Higher total contribution
- Potentially higher future value
Sabse zaroori baat: Step-Up SIP ka main mechanism investment return badhana nahi hai. Yeh sirf higher contribution over time deta hai. Upar ke difference ka main reason ₹3.56 lakh ka extra contribution hai (₹9.56 lakh minus ₹6.00 lakh), higher rate of return nahi.
Step-Up SIP Ke 5 Benefits
Income Ke Saath Investment Badhna
Salary badhne par SIP amount ko planned tareeke se badha sakte ho.
Long-Term Goal Planning
Bade goals ke liye gradually badhta contribution useful ho sakta hai.
Inflation Ke Saath Chalne Mein Help
Nominal contribution badhta hai, par yeh inflation ko automatically beat nahi karta.
Investment Discipline
Pre-planned increase se har saal manually SIP badalne ka decision kam hota hai.
Compounding Ko Zyada Capital
Zyada invested capital market growth mein participate kar sakta hai. Outcome guaranteed nahi.
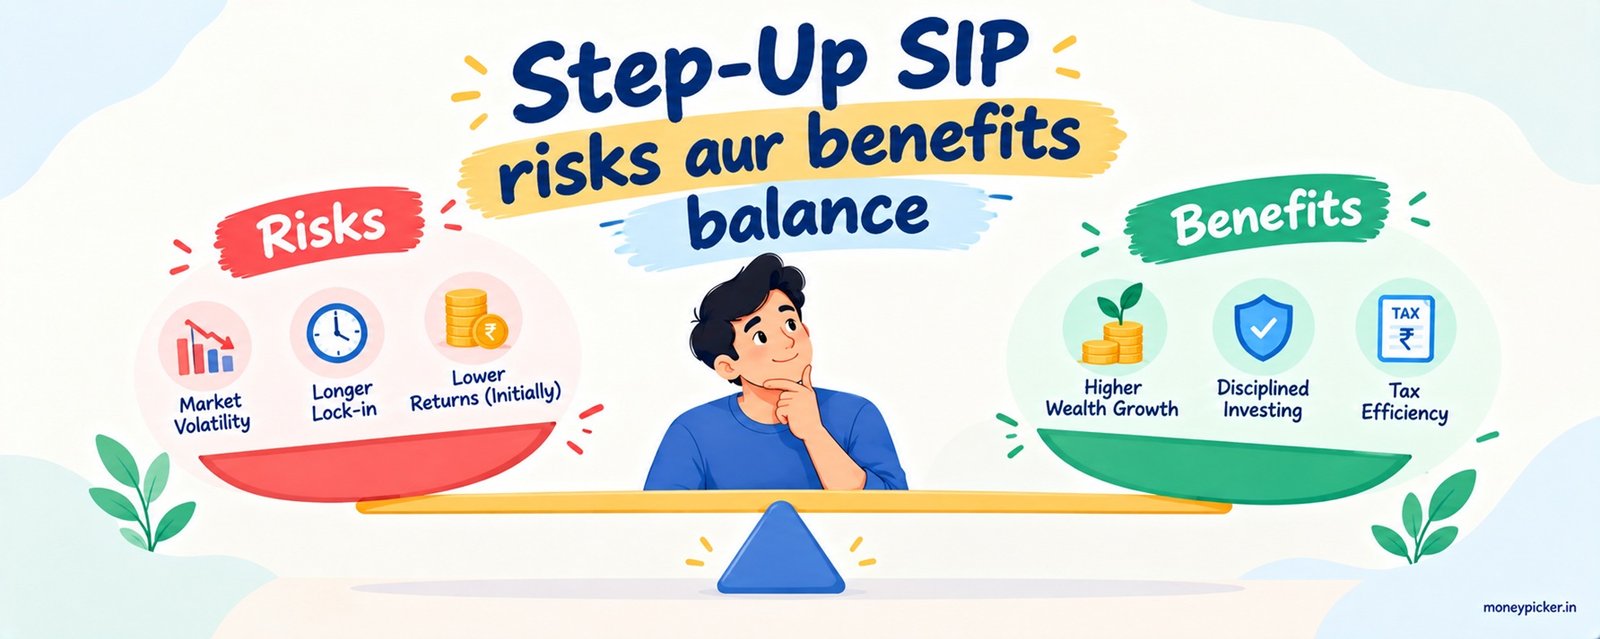
Step-Up SIP Ke Risks aur Limitations
Income Stable Na Ho
Contribution badhta rahe aur income nahi, toh cash-flow pressure aa sakta hai.
Overly Aggressive Step-Up
Har saal 15-20% increase sabke liye realistic nahi hota.
Market Risk Rehta Hai
Step-up se market risk khatam nahi hota. NAV upar-neeche hota rehta hai.
Higher Contribution, Guaranteed Return Nahi
Invested capital badhta hai, par returns market-linked hi rehte hain.
Goal aur Cash Flow Mismatch
Future expenses dekhe bina increase rate choose karna risky ho sakta hai.
Automatic Increase Review Karo
Life circumstances badalti hain, isliye plan ko review karte raho.
Mutual fund risks samajhne ke liye SEBI Investor Website dekhein.
Step-Up ke Saath Inflation aur Compounding
Agar SIP 10 saal tak ₹5,000 hi rahe, toh inflation se uski purchasing power kam ho sakti hai. Maan lo inflation 6% hai (illustrative assumption). Tab 10 saal baad ₹5,000 ki value aaj ke lagbhag ₹2,792 ke barabar hogi.
Step-Up SIP nominal contribution badhata hai, lekin yeh inflation-proof guarantee nahi hai.
Compounding ka matlab hai ki zyada contribution zyada time tak invested rahe toh zyada capital market-linked growth mein participate karta hai. Par returns fixed nahi hote, aur compounding profit ki guarantee nahi deta. “Paisa double ho jata hai” jaisa claim misleading hai.
Financial Goals aur Step-Up Rate
Step-up percentage goal se judna chahiye. Yeh flow follow kar sakte ho:
- Goal
- Current SIP
- Expected income growth
- Step-Up rate
- Time horizon
- Required contribution
- Periodic review
Retirement
Lamba horizon; corpus need review karo.
Child’s Education
Fees inflation dhyan mein rakho.
Home Down Payment
Chhoti timeline mein aggressive step-up aur market risk sochein.
Long-Term Wealth Goal
Sustainable increase zyada matter karta hai.
Financial Safety Basics Pehle
Contribution badhane se pehle emergency savings, insurance protection aur high-interest debt dekhna zaroori ho sakta hai. Overall position samajhne ke liye MoneyPicker ka Financial Health Score Calculator ek useful starting point ho sakta hai.
SIP Mein Kitna Step-Up Karein?
Koi universal percentage nahi hota. Income growth, expenses, inflation, savings, goals, debt, emergency fund, risk tolerance aur horizon dekhna padega. ₹50,000/month aur ₹2 lakh/month kamane walon ka sustainable rate alag ho sakta hai, kyunki EMI aur responsibilities alag hoti hain.
| Annual increase | Year 10 monthly SIP | 10-year total contribution |
|---|---|---|
| 5% | ≈ ₹7,757 | ≈ ₹7.55 lakh |
| 10% | ≈ ₹11,790 | ≈ ₹9.56 lakh |
| 15% | ≈ ₹17,589 | ≈ ₹12.18 lakh |
Salary Growth + Step-Up Example (Hypothetical)
Maan lo salary ₹50,000 hai, SIP ₹5,000, aur salary har saal 8% badhti hai. SIP bhi 8% badhe toh woh salary ka lagbhag 10% rehti hai. Salary increase guaranteed nahi hota; yeh sirf ek scenario hai.
| Year | Monthly salary | Monthly SIP | SIP share |
|---|---|---|---|
| 1 | ₹50,000 | ₹5,000 | 10% |
| 2 | ₹54,000 | ₹5,400 | 10% |
| 3 | ₹58,320 | ₹5,832 | 10% |
| 4 | ₹62,986 | ₹6,299 | 10% |
| 5 | ₹68,024 | ₹6,802 | 10% |
Step-Up SIP Kab Choose Karein?
Yeh general considerations hain, personalized advice nahi. Yeh option sabke liye nahi hota.
Consider it if:
- Income reasonably stable hai
- Long-term goal hai
- Contribution increase affordable hai
- Emergency savings aur protection basics covered hain
- Manual yearly SIP change nahi chahte
Reconsider if:
- Income highly unpredictable hai
- Monthly budget already stretched hai
- Major near-term expenses expected hain
- High-interest debt se cash flow tight hai
- Emergency savings kam hain
Step-Up SIP Decision Checklist
- Income reasonably stable hai?
- Emergency savings in place hain?
- High-interest debt under control hai?
- Goal long-term hai?
- Monthly contribution badha sakte ho?
- Future expenses consider kiye?
- Step-up percentage realistic hai?
Agar kai jawab “No” hain, toh planned increase ko blindly badhane ke bajaye reconsider karna better ho sakta hai.
| Situation | Regular SIP | Step-Up |
|---|---|---|
| Fixed income | May be easier | Careful planning chahiye |
| Rising salary | Can work | Planned increases se align ho sakta hai |
| Irregular income | More predictable | Zyada flexibility chahiye ho sakti hai |
| Long-term goal | Can work | Can be useful |
| Tight monthly budget | May be easier | Future contribution ki planning zaroori |
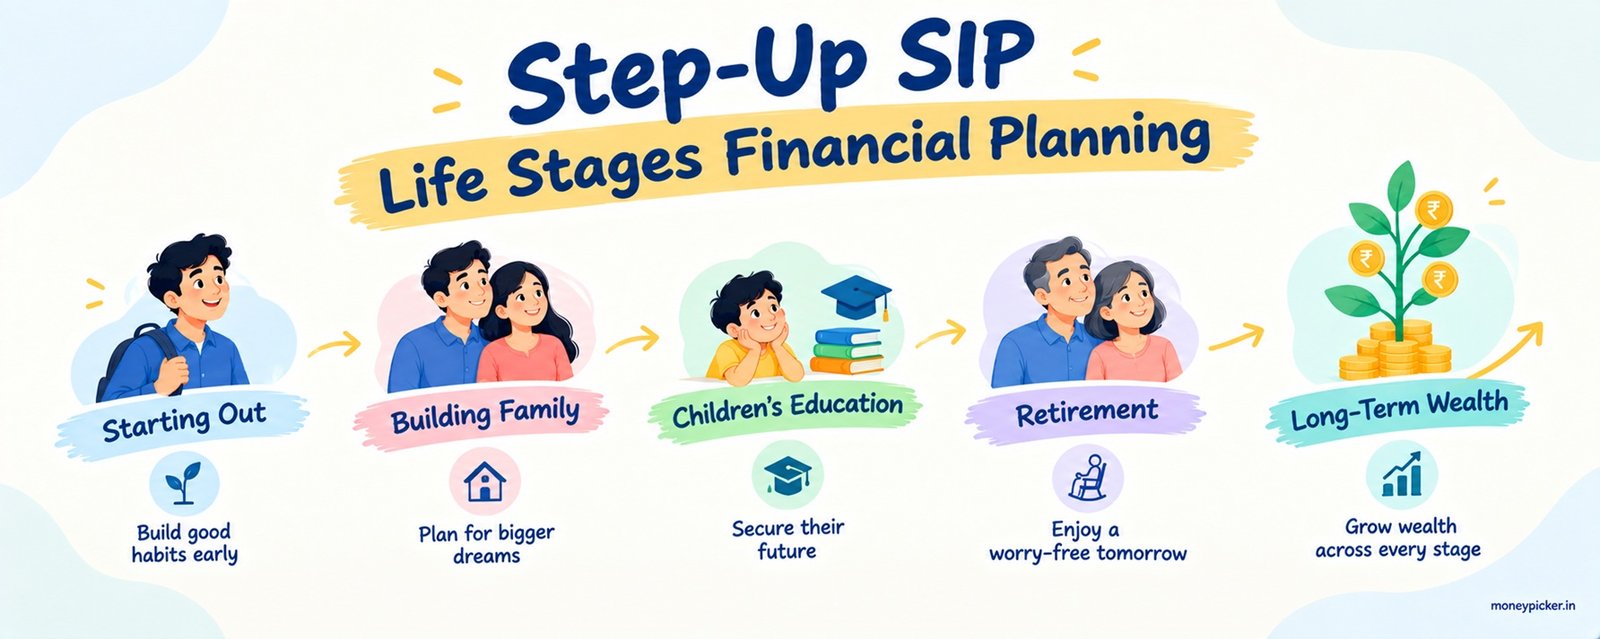
Life Stage Examples: Kaun Kab Step-Up Kare?
Har kisi ki life same path par nahi chalti. Yeh sirf general ideas hain:
Student / First Job
Chhota start karo, discipline banao, unrealistic increase se bacho.
Early Career
Income badhe toh gradual increase consider karo.
Family Stage
Multiple goals aur realistic cash flow balance karo.
Pre-Retirement
Required corpus, capacity aur risk review karo; aggressive assumptions se bacho.
Common Step-Up Mistakes
- Unrealistic step-up percentage choose karna
- Future expenses ignore karna
- Emergency savings ke bina SIP badhana
- Higher contribution ko higher return samajhna
- Salary increase ko certain maan lena
- Market risk ignore karna
- Major life change ke baad review na karna
- Sirf isliye rate choose karna kyunki koi aur use karta hai
- Short-term volatility se poora plan bina samjhe stop kar dena
- Sirf corpus projection dekhna, affordability ignore karna
Myths vs Facts
Step-Up SIP bigger return guarantee karta hai.
Yeh planned contribution badhata hai; returns market-linked rehte hain.
Higher step-up percentage hamesha better hai.
Increase cash flow aur goals ke hisaab se sustainable hona chahiye.
Step-up ke baad review ki zaroorat nahi.
Goals, income, expenses aur risk capacity badal sakte hain.
Step-up sirf high-income logon ke liye hai.
Concept alag contribution levels par adapt ho sakta hai, agar increase affordable ho.
Apna Step-Up SIP Plan Banane Ke 7 Steps
- Goal define karo: paisa kis kaam ke liye chahiye.
- Initial SIP choose karo jo comfortably afford ho.
- Investment horizon estimate karo.
- Realistic step-up amount ya percentage choose karo.
- Monthly cash-flow affordability check karo.
- Plan ko periodically review karo.
- Hypothetical scenarios explore karo MoneyPicker ke Step-Up SIP Calculator se.
Planning Worksheet
Khaali columns khud bharo.
| Goal | Initial SIP | Step-Up % / Amount | Time Horizon | Monthly Contribution Later | Review Date |
|---|---|---|---|---|---|
| Retirement | |||||
| Child Education | |||||
| Home | |||||
| Wealth Goal |
MoneyPicker Step-Up SIP Calculator
Alag Step-Up percentages aur periods ke saath apna hypothetical projection dekhna chahte ho? Yeh calculator useful starting point ho sakta hai. Result estimate hota hai, guarantee nahi.
Step-Up SIP Calculator kholo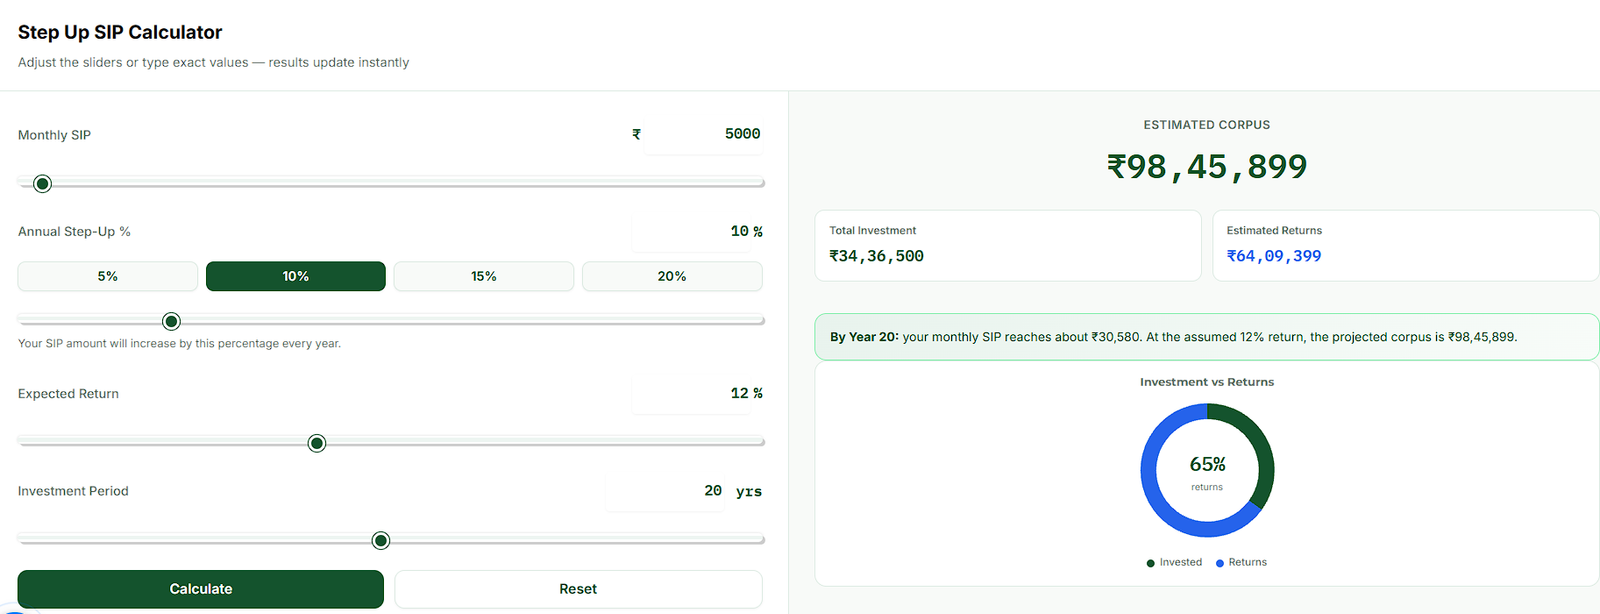
Step-Up SIP FAQs
Step-Up SIP kya hota hai?
Yeh SIP ka option hai jisme contribution pre-decided schedule par badhta hai, fixed percentage ya fixed amount se. Increase tabhi hota hai jab aap yeh option select karte ho.
Step-Up SIP kaise kaam karta hai?
Aap initial SIP, increase ka tareeka aur timing choose karte ho, aur contribution instruction ke hisaab se badhta hai. Exact process platform ya AMC ke hisaab se alag ho sakti hai.
SIP mein kitna step-up karna chahiye?
Koi universal percentage nahi hai. Income, expenses, goals, debt aur emergency fund dekhkar sustainable rate choose karein. 5%, 10% ya 15% sirf examples hain.
Kya Step-Up SIP guaranteed return deta hai?
Nahi. Mutual fund returns market-linked hote hain. Yeh option sirf contribution badhata hai, return ka rate nahi.
Yeh option kab choose karna chahiye?
Jab income reasonably stable ho, goal long-term ho aur contribution badhana affordable ho, tab consider kiya ja sakta hai.
Kya SIP step-up beech mein change ya stop ho sakta hai?
Aam taur par SIP instructions modify ya stop ki ja sakti hain, lekin process aur timelines platform ya AMC par depend karte hain.
Percentage aur fixed amount step-up mein kya difference hai?
Percentage step-up current SIP par calculate hota hai, isliye rupee increase badhta jata hai. Fixed-amount mein har baar same rupee amount add hota hai.
Step-Up SIP ka calculation kaise karein?
Initial SIP, yearly increase, duration aur assumed return ko formula ya calculator mein daalte hain. Result sirf estimate hota hai.
Kya step-up se market risk kam hota hai?
Nahi. NAV market ke saath upar-neeche hota hai. Contribution badhne se absolute loss ka size bhi badh sakta hai.
Step-Up SIP Calculator kaise use karein?
Starting SIP, annual step-up, duration aur assumed return daalein, aur alag assumptions try karke dekhein. Output guaranteed nahi hota.
Disclaimer: This article is for educational purposes only and does not constitute personalized financial or investment advice. Mutual fund investments are subject to market risks, and returns are not guaranteed. Examples and calculations in this article use hypothetical assumptions.
Useful resources: Aur beginner-friendly guides aur free tools ke liye MoneyPicker.in visit karein.