
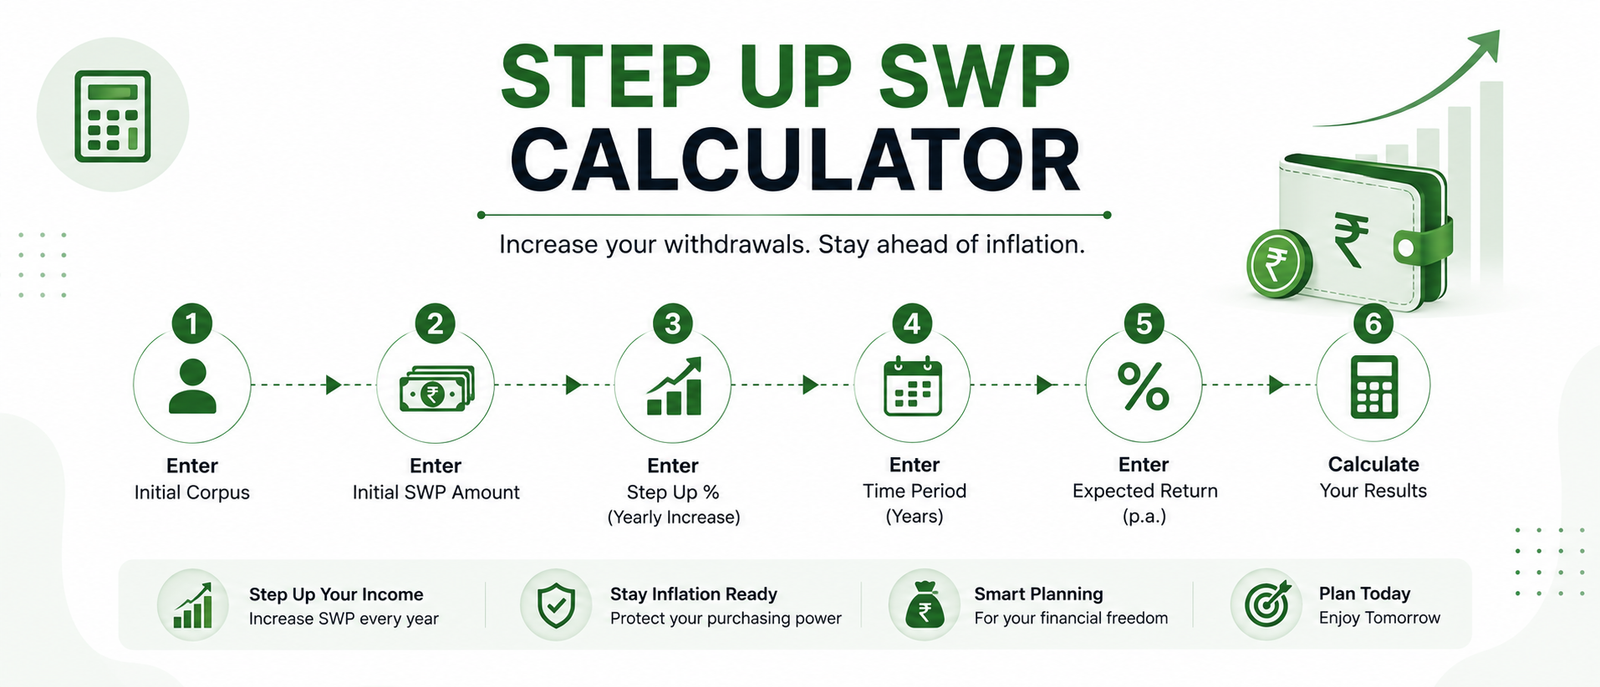
Step Up SWP Calculator
See how long your investment corpus may last with a monthly withdrawal that increases every year.
How to Use This Step Up SWP Calculator
- Enter your Initial Investment — the lump sum corpus you already have invested and plan to withdraw from.
- Set your Monthly SWP — how much you want to withdraw each month, starting from Year 1.
- Choose your Annual Step-Up % using the quick buttons (5%, 10%, 15%, 20%) or type in a custom percentage — this is how much your withdrawal will increase every year.
- Set your Expected Return and Duration to match your investment assumptions and time horizon.
- That’s it — there’s no need to click anything. As soon as you move any slider, your Corpus Duration, Remaining Corpus, Total Withdrawn and the chart all update instantly (the Calculate button is there too, if you prefer clicking it).
- Check the status message at the top of the results — it tells you plainly whether your corpus is projected to last the full duration, or roughly when it may run out.
- Scroll down to compare Regular SWP vs Step-Up SWP side by side, see exactly how your withdrawal grows year by year in the table, and use the chart toggle to switch between Corpus Balance and Withdrawals view.
Regular SWP vs Step-Up SWP
Corpus Balance Over Time
How Your SWP Increases Every Year
Year-Wise Withdrawal Schedule
| Year | Monthly SWP | Annual Withdrawal | Total Withdrawn | Remaining Corpus |
|---|
What is an SWP?
A Systematic Withdrawal Plan (SWP) lets you withdraw a fixed amount from your mutual fund investment at regular intervals, typically every month, while the rest of your corpus stays invested and continues to grow. Mutual funds in India are regulated by the Securities and Exchange Board of India (SEBI), and you can find investor education resources on SWP and other mutual fund features on the AMFI (Association of Mutual Funds in India) website.
What is a Step-Up SWP?
A Step-Up SWP increases your monthly withdrawal by a fixed percentage every year, instead of keeping it constant. This helps your withdrawals keep pace with rising expenses and inflation over a long retirement or income period.
How Does Step-Up SWP Work?
Each month, your remaining corpus first earns the expected return, then your current monthly withdrawal is deducted from it. At the end of every year, the withdrawal amount increases by your chosen step-up percentage, and the higher amount continues into the next year.
Step-Up SWP Example
Starting corpus ₹25,00,000, monthly SWP ₹20,000, step-up 5% a year, expected return 10% a year. Your monthly withdrawal rises from ₹20,000 in year 1 to over ₹50,000 by year 20 — see your own numbers in the table above.
Step-Up SWP vs Regular SWP
A regular SWP withdraws the same amount every month for the entire period, while a Step-Up SWP increases the withdrawal every year. A Step-Up SWP better matches rising real-world expenses but can also exhaust your corpus sooner than a regular SWP if the withdrawal rate grows faster than your investment returns. Note that SWP withdrawals may attract capital gains tax depending on your fund type and holding period — check current rules on the Income Tax Department website.