Insurance for Beginners: Term & Health Insurance Explained + Kaunsa Insurance Zaroori Hai?
Socho: aapke paas savings hai, thoda SIP bhi chal raha hai, aur ek small emergency fund bhi bana rakha hai. Sab kuch theek chal raha hai — phir achanak ghar mein koi hospitalise ho jaata hai, ya family ka main earning member nahi rehta. Is tarah ke events, savings aur investments jitni bhi acchi ho, unn par bada dent daal sakte hain.
Yahi wo gap hai jo insurance fill karta hai. Financial planning sirf “kitna invest karu” tak limited nahi hai — usme “agar kuch bada risk ho jaaye to kya hoga” ka jawab bhi hona chahiye. Ye insurance for beginners guide bilkul shuru se banaya gaya hai — is article mein hum insurance ko bilkul beginner level se samjhenge — especially Term Insurance aur Health Insurance, jo har Indian ke liye sabse zyada relevant categories hain.
Insurance Kya Hai?
Simple bhasha mein, insurance ek aisa financial arrangement hai jisme aap ek insurance company (insurer) ko ek chhoti si regular amount dete ho, jise premium kehte hain. Badle mein, insurer promise karta hai ki agar policy mein define kiya gaya koi specific event ho jaaye — jaise hospitalisation ya insured person ki death policy term ke andar — to wo ek defined financial amount pay karega, policy ke terms ke according.
Isse thoda aur break karte hain:
- Risk transfer: Aap apna financial risk (jaise bada hospital bill) insurance company ko “transfer” kar rahe ho, ek chhote premium ke badle.
- Policy: Wo legal document jisme coverage, terms, exclusions aur conditions likhi hoti hain.
- Coverage / Sum Assured / Sum Insured: Maximum amount jo policy ke under milna possible hai, terms ke mutabik.
- Claim: Jab covered event hota hai aur aap insurer se payment ke liye request karte ho, use claim kehte hain.
- Insured / Policyholder: Jis person ka risk cover kiya gaya hai (health insurance mein alag ho sakta hai jo premium pay kar raha hai).
- Nominee: Wo person jise policyholder ne claim amount receive karne ke liye designate kiya hai (especially life/term insurance mein important).
Example: Socho aap aur aapke 99 padosi milkar ek fund banate ho — har koi ₹1,000 daalta hai. Agar kisi ek ke ghar mein aag lag jaaye, to fund se uski help ho jaati hai. Insurance companies isi concept ko bade scale par, professionally aur regulated tareeke se run karti hain. Yehi concept samajhna is insurance for beginners guide ka sabse pehla step hai.
Insurance ka Basic Purpose: Protection, Na Ki Wealth Creation
Beginners jo sabse common confusion karte hain wo hai insurance ko investment samajh lena. In dono ka purpose bilkul alag hai, aur emergency fund bhi ek teesra alag concept hai.
Insurance
Primarily risk protection — kisi specific bade financial risk (health cost, death of earning member) ke impact ko reduce karna.
Investment
Primarily wealth creation — long-term mein paisa grow karne ke liye, market-linked ya other growth instruments ke through.
Emergency Fund
Short-term liquidity buffer — chhote-mote unexpected expenses ya income gap ke liye readily available cash.
| Aspect | Insurance | Savings | Investment | Emergency Fund |
|---|---|---|---|---|
| Main Goal | Risk protection | Money accumulation | Long-term wealth creation | Short-term buffer |
| Trigger | Specific covered event | Anytime | Goal-based, long horizon | Any urgent need |
| Liquidity | Usually low/conditional | High | Varies by instrument | Very high |
| Ideal Use | Large, low-probability risks | Near-term needs | Long-term goals | 3–6 months’ expenses (commonly considered) |
Agar aap insurance planning ke baad apne long-term investment goals ko roughly estimate karna chahte hain, SIP Calculator se ek basic projection dekh sakte hain.
Types of Insurance in India
India mein consumers ke liye kai insurance categories relevant ho sakti hain. Is insurance for beginners article ka main focus Term aur Health Insurance hai, lekin baaki categories ko bhi jaanna zaroori hai.
Iske alawa Personal Accident Insurance aur profession/lifestyle-specific covers bhi available hain. Kaunsi categories aapke liye relevant hain, ye depend karta hai aapke assets, liabilities, travel pattern aur profession par. Insurance protection set karne ke baad, apne overall financial plan ko organize karne ke liye aap MoneyPicker.in par available free calculators aur guides bhi explore kar sakte hain.
Term Insurance Kya Hai?
Term Insurance ek pure life insurance product hai jo ek fixed policy term (jaise 20 ya 30 saal) ke liye life cover deta hai. Agar policyholder ki death policy term ke andar ho jaati hai, to nominee ko ek predefined death benefit milta hai, policy ke terms ke according.
Key concepts:
- Policy Term: Wo duration jiske liye cover active rehta hai.
- Sum Assured: Wo amount jo death hone par nominee ko milta hai.
- Premium: Regular payment jo policyholder insurer ko karta hai cover maintain rakhne ke liye.
- Death Benefit: Actual payout jo claim approve hone par diya jaata hai.
Pure term insurance primarily protection-oriented hota hai — iska main design purpose investment return dena nahi, balki dependents ko financial security dena hai agar earning member na rahe. Iss wajah se, term insurance for beginners ko samajhna thoda tricky lag sakta hai, lekin concept simple hai. Agar policy term khatam hone tak policyholder alive rehta hai, to plain term plans mein generally koi maturity payout nahi milta (kuch variants alag structure follow karte hain — isse aage discuss karenge).
Term Insurance — Ek Simple Example
Socho ek 30-year-old individual, jiske spouse aur ek chhota bachcha hai, ek term insurance policy leta hai. Wo har saal ek defined premium pay karta hai. Agar policy term ke dauran unki death ho jaati hai, to nominee (yahan spouse) ko sum assured milta hai — jo unke family ko immediate financial stability de sakta hai (jaise EMI, education expenses, daily living costs).
Actual premiums age, health condition, smoking status, policy term, sum assured aur insurer ke underwriting process ke hisaab se vary karte hain — is article mein koi specific premium figure isliye nahi diya gaya hai.
Term Insurance Kisko Chahiye?
Term insurance especially un logon ke liye relevant hota hai jinke paas:
- Financial dependents (spouse, children, dependent parents)
- Outstanding liabilities (jaise home loan, personal loan)
- Long-term financial obligations (jaise children ki future education)
Agar kisi individual ke koi dependents nahi hain aur unke paas sufficient assets already available hain, unki term insurance ki need alag ho sakti hai. Ye ek “sabke liye zaroori hai” wali cheez nahi hai — ye purely situation-dependent hota hai. Yehi flexibility insurance for beginners ke liye samajhna zaroori hai.
Term Cover Kitna Rakhein? Kaise Sochein
Cover amount decide karte waqt in factors ko consider kiya jaa sakta hai:
- Income replacement need (dependents kitne saalon tak depend karenge)
- Outstanding loans aur liabilities
- Future responsibilities jaise children ki education
- Existing investments/assets jo already available hain
- Inflation ka asar future expenses par
- Koi existing insurance coverage jo already hai
Koi bhi ek fixed formula har person ke liye sahi nahi hota — ye ek framework hai sochne ke liye, universal rule nahi. Home loan wale readers EMI Calculator se apni outstanding liability ka rough estimate nikaal sakte hain, jo cover amount sochte waqt useful ho sakta hai.
Health Insurance Kya Hai?
Health Insurance ek policy hai jo hospitalisation aur medical treatment se related specified expenses ko, policy ke terms ke according, cover karti hai. Ye section health insurance for beginners ke liye especially likha gaya hai, taaki basic terms clearly samajh aayein.
- Sum Insured: Maximum amount jo ek policy year mein claim ke through use ho sakta hai.
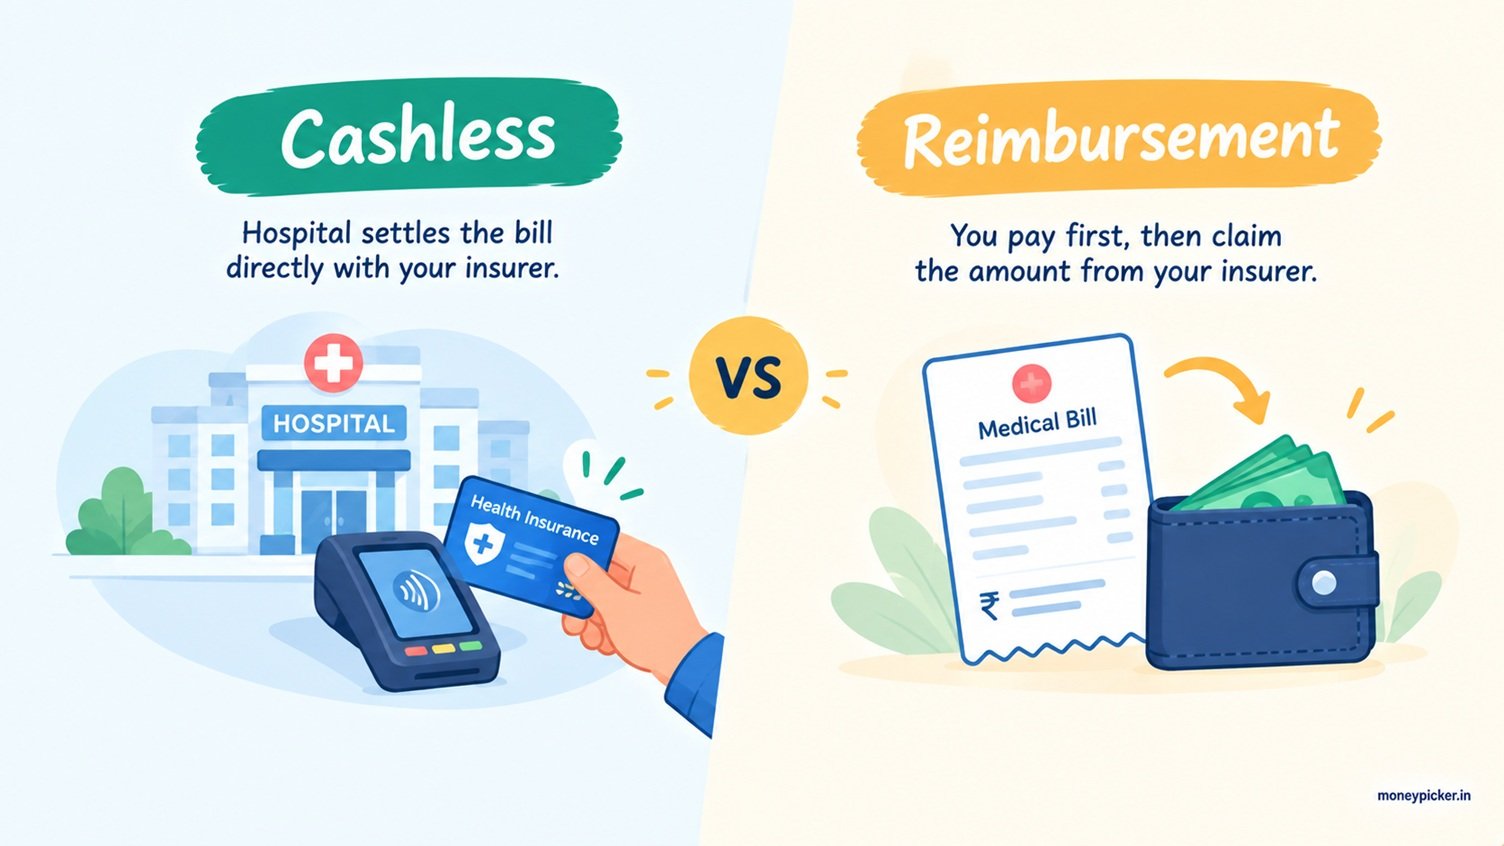
- Cashless Treatment: Network hospital mein bina upfront full payment ke treatment, insurer directly hospital ko settle karta hai (policy terms ke mutabik).
- Reimbursement: Pehle khud payment karke, baad mein insurer se claim karke amount wapas lena.
- Network Hospitals: Wo hospitals jinke saath insurer ka tie-up hota hai.
- Waiting Period: Wo initial duration jisme specified conditions ke liye coverage start nahi hoti.
- Exclusions: Wo situations/treatments jo policy cover nahi karti.
- Deductible: Ek amount jo policyholder ko khud bear karna padta hai claim se pehle.
- Co-payment: Claim amount ka ek fixed percentage jo policyholder ko share karna hota hai.
Health Insurance Kyun Zaroori Hai
Medical treatment — especially hospitalisation, surgeries ya prolonged illness — significant financial pressure create kar sakta hai. Health insurance is pressure ko manage karne ke liye design kiya gaya hai, lekin ye important hai samajhna ki coverage hamesha policy ke terms, conditions, exclusions aur limits par depend karti hai — har medical expense automatically covered nahi hota.
Cashless vs Reimbursement
| Feature | Cashless | Reimbursement |
|---|---|---|
| How it generally works | Insurer directly settles bill with network hospital, subject to approval | Policyholder pays first, then submits documents for reimbursement |
| Payment flow | Minimal upfront payment (subject to approval & policy terms) | Full upfront payment by policyholder |
| Network hospital relevance | Generally available only at network hospitals | Usually available at both network & non-network hospitals |
| Important consideration | Approval process aur documentation timelines insurer/policy specific hote hain | Requires careful bill/document collection for a smooth claim |
Exact process insurer aur specific policy ke hisaab se differ kar sakta hai — apni policy wording zaroor check karein.
Waiting Period, Exclusions & Sub-limits
Ye teeno concepts insurance for beginners ke liye sabse zyada important hain, kyunki inhe samjhe bina log galat expectation le lete hain.
- Waiting Period: Kuch specified conditions ya treatments policy start hone ke turant baad cover nahi hote — ek defined waiting period ke baad hi cover applicable hota hai.
- Exclusions: Kuch situations ya treatments policy mein permanently cover nahi kiye jaate.
- Sub-limits: Kuch specific expenses (jaise room rent) par ek maximum limit set hoti hai, chahe overall sum insured zyada ho.
Term Insurance vs Health Insurance
Term Insurance
- Covers: Death during policy term
- Beneficiary: Nominee
- Purpose: Income replacement for dependents
- Trigger: Death of the insured
Health Insurance
- Covers: Hospitalisation / medical expenses
- Beneficiary: Policyholder / insured person
- Purpose: Medical cost protection
- Trigger: Hospitalisation / covered medical event
| Feature | Term Insurance | Health Insurance |
|---|---|---|
| Primary purpose | Income replacement for dependents | Medical expense protection |
| Main risk covered | Death of the insured within policy term | Hospitalisation / medical treatment costs |
| Beneficiary/claim recipient | Nominee | Policyholder / insured person |
| Typical trigger for claim | Death of insured | Hospitalisation or covered medical event |
| Coverage type | Lump-sum death benefit | Medical expense reimbursement/cashless |
| Why it matters | Protects dependents’ financial future | Reduces the financial burden of treatment |
| Who may especially need it | People with financial dependents/liabilities | Almost everyone, regardless of dependents |
In dono policies alag-alag financial risks solve karti hain. Ek generally doosre ka replacement nahi hai.
“Kaunsa Insurance Zaroori Hai?” — Insurance for Beginners Decision Framework
Iska koi ek universal answer nahi hai — lekin ek simple decision framework help kar sakta hai:
Insurance Priority Matrix
| Situation | Insurance to Consider |
|---|---|
| No dependents + salaried | Health insurance; term cover may depend on individual circumstances |
| Married + dependent spouse | Health insurance + term insurance may be important |
| Have children/dependents | Health insurance + term insurance |
| Large home loan | Health insurance + term insurance may be particularly relevant |
| Own a vehicle | Motor insurance |
| Frequent international travel | Travel insurance may be relevant |
| Self-employed/freelancer | Health insurance + income-protection considerations; term cover depending on dependents |
Home loan wale readers apni liability ko EMI Calculator se estimate kar sakte hain, jo insurance planning ke context ko clearer banata hai. (Ye general educational guidance hai, personalized financial advice nahi.)
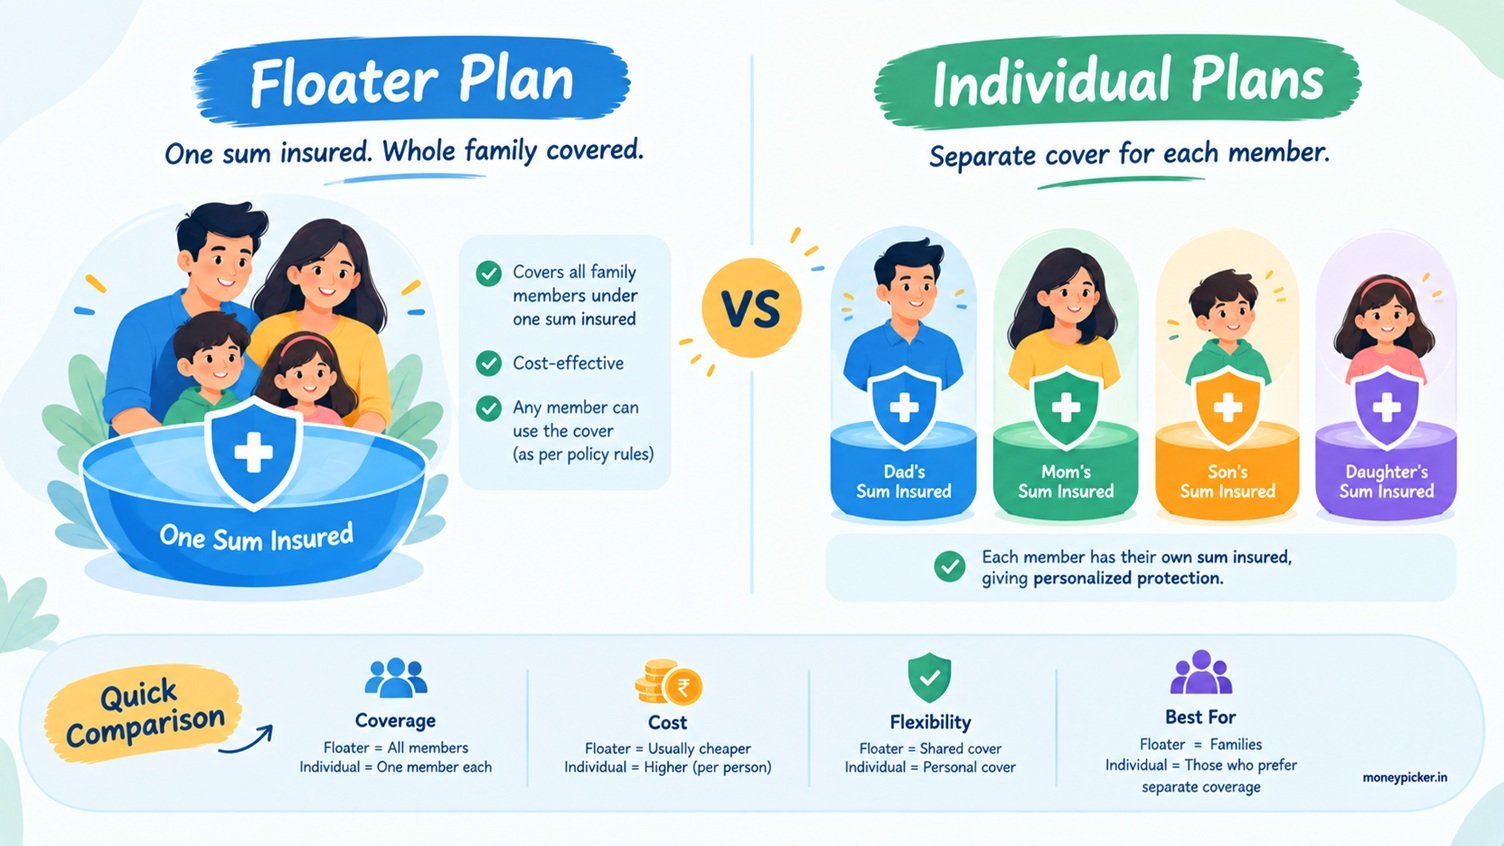
Health Insurance — Individual vs Family Floater
Individual Health Insurance: Har family member ka apna separate sum insured hota hai.
Family Floater: Ek hi sum insured pure family ke beech “share” hota hai — koi bhi member usme se claim kar sakta hai, jab tak sum insured available hai.
Individual Cover
- Har member ka apna separate sum insured
- Ek member ka claim doosre ke cover ko touch nahi karta
- Premium generally har member ke liye alag calculate hota hai
Family Floater
- Ek shared sum insured, pure family ke liye
- Koi bhi member zyada use kar sakta hai, jab tak pool available hai
- Often cost-efficient for younger, smaller families
Kaunsa structure relevant hai, ye family size, age profile aur health history par depend karta hai — dono mein se koi bhi “hamesha better” nahi hota.
Health Insurance — Buying Se Pehle Kya Check Karein
Health Insurance Checklist
- Sum insured — kya ye adequate hai city aur family size ke hisaab se?
- Network hospitals — nearby aur trusted hospitals list mein hain?
- Waiting periods — kaunse conditions ke liye kitna wait karna hoga?
- Exclusions — kya specifically cover nahi hota?
- Room-rent limits — kya room type par koi cap hai?
- Co-payment aur deductibles — policyholder ka share kitna hoga?
- Sub-limits — kis expense par cap hai?
- Pre-existing disease provisions — kaise treat hote hain?
- Restoration/reinstatement features — agar applicable ho to kaise kaam karte hain?
- Claim process — cashless aur reimbursement dono clear hain?
- Renewal terms — kya conditions hain?
- Policy wording — pura document padha hai?
Term Insurance — Buying Se Pehle Kya Check Karein
Term Insurance Checklist
- Sum assured — dependents aur liabilities ke hisaab se adequate hai?
- Policy term — working years aur responsibilities ke saath align karta hai?
- Premium affordability — long-term tak comfortably pay kar sakte hain?
- Claim-related terms clearly samajh liye hain?
- Nominee details correctly filled hain?
- Medical disclosures accurate diye hain?
- Exclusions/conditions padhi hain?
- Policy wording completely review kiya hai?
- Insurer ki reliable, current, publicly available information dekhi hai?
- Premium payment term samajh liya hai?
- Riders — sirf genuinely useful hone par hi liye hain?
Medical Disclosure — Important
Insurance apply karte waqt accurate information dena bahut zaroori hai — jaise smoking status, existing medical conditions, previous diagnoses/treatments, aur relevant medical history. Kam premium pay karne ke liye information chhupana risky ho sakta hai — inaccurate ya incomplete disclosure future claims mein serious issues create kar sakta hai, policy terms aur applicable rules ke hisaab se.
Nominee Ka Role
Nominee wo person hota hai jise policyholder ne claim amount receive karne ke liye designate kiya hai. Nominee details ko update rakhna important hai, especially major life events ke baad (jaise marriage, children ka birth). Nominee ke exact legal rights aur succession-related aspects policy type aur applicable law par depend kar sakte hain — is baare mein detailed legal clarity ke liye professional advice lena helpful ho sakta hai.
Insurance Premium vs Coverage
Ek common beginner mistake hai sochna ki “cheap premium = best policy.” Actually premium ko coverage, exclusions, limits, policy terms, claim process aur overall suitability ke saath dekhna chahiye. Kisi bhi insurer ko bina reliable, current evidence ke “best” declare karna misleading ho sakta hai. Premium ek recurring outgo hai, isliye ise apne monthly budget ke saath bhi align karna zaroori hai — agar aap already kisi loan ki EMI bhi manage kar rahe hain, to EMI Calculator se overall monthly outgo ka clearer picture mil sakta hai.
Insurance vs Investment
Insurance ka primary focus risk protection hai, jabki investment ka primary focus wealth creation hai. Ye zaroori nahi ki har insurance-linked savings product “bad” ho — har financial product ko uske purpose, cost, risk, liquidity aur suitability ke basis par evaluate karna chahiye, na ki sirf category ke naam par.
Agar protection planning complete ho chuki hai aur aap apne long-term goals ko plan karna chahte hain, ₹1 Crore Calculator se ek rough estimate dekh sakte hain ki goal tak pahunchne mein kitna time/investment lag sakta hai.
Illustrative structure only — your actual allocation depends on income, dependents and goals, not a fixed rule.
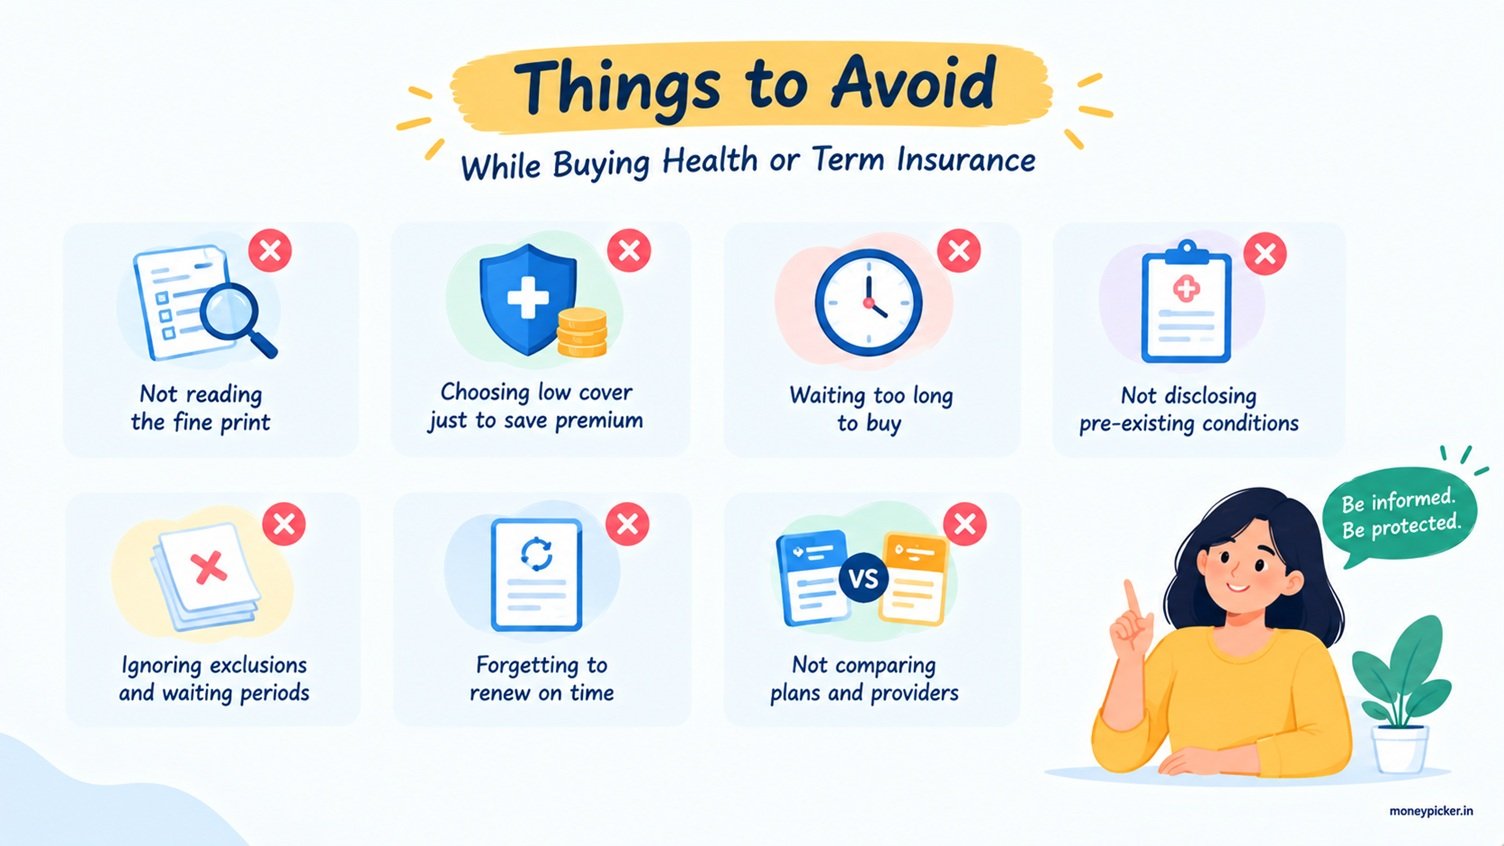
Common Insurance Mistakes
In mistakes ko avoid karna kisi bhi insurance for beginners journey ka important hissa hai:
- Sirf agent ki recommendation par buy karna: Apni khud ki need samajhna zaroori hai.
- Sirf low premium dekh kar choose karna: Coverage aur exclusions bhi check karein.
- Exclusions na padhna: Policy document carefully review karein.
- Waiting periods ignore karna: Ye samajhna zaroori hai ki cover kab se effective hoga.
- Health coverage underestimate karna: Rising medical costs ko consider karein.
- Dependents consider kiye bina insufficient term cover lena.
- Medical information chhupana.
- Nominee details update na karna.
- Bina samjhe unnecessary riders lena.
- Insurance aur investment goals ko mix karna bina product samjhe.
- Poor planning ki wajah se policy lapse ho jaana.
- Har medical expense covered maan lena.
- Sirf employer health insurance par depend karna, portability/continuity consider kiye bina.
Employer Health Insurance — Kya Ye Kaafi Hai?
Employer-provided health insurance useful ho sakta hai, lekin insurance for beginners ko in points ko evaluate karna chahiye:
- Coverage limits — kya sum insured adequate hai?
- Family coverage — kya sabhi dependents included hain?
- Employment dependency — cover job ke saath linked hota hai
- Job change hone par kya hota hai
- Policy continuity considerations
Employer insurance automatically insufficient nahi hota — lekin ye evaluate karna zaroori hai ki wo aapki actual needs ke saath match karta hai ya nahi.
Insurance Claims — Basic Process
High-level overview — kisi bhi insurance for beginners ke liye ye samajhna helpful hota hai ki claim process kaise kaam karta hai:
Health insurance mein broadly do process hote hain — cashless (network hospital ke through) aur reimbursement (pehle khud pay karke). Exact timelines aur approval process insurer aur policy specific hote hain — koi bhi claim automatically guaranteed nahi hota. Agar kisi claim ko lekar insurer ke saath dispute resolve nahi ho paata, to policyholders Insurance Ombudsman ke through grievance redressal ka option bhi explore kar sakte hain.
Insurance Document Checklist
Documents Jo Accessible Rakhein
- Policy document
- Premium payment records
- Nominee details
- Insurer contact information
- Customer ID / policy number
- Relevant medical documents
- Claim procedure information
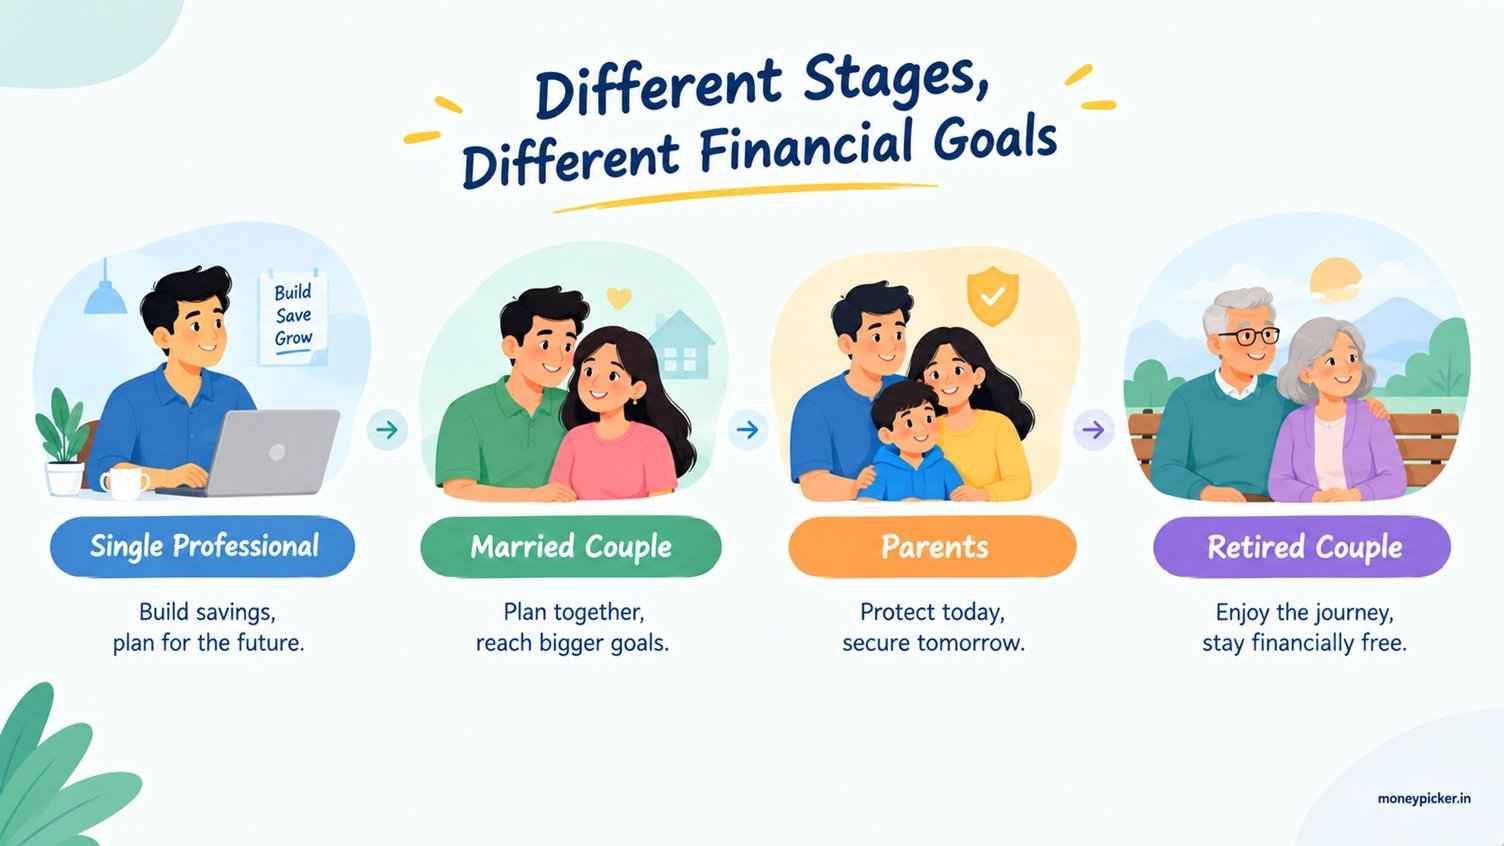
Insurance for Different Life Stages
| Life Stage | What Generally Becomes Relevant |
|---|---|
| Young professional | Health insurance early; term cover depending on dependents |
| Newly married | Reviewing/updating existing health & term cover, nominee updates |
| Parents with children | Health + term insurance become particularly relevant |
| Home loan borrower | Term cover consideration alongside health insurance |
| Self-employed/freelancer | Health insurance + income-protection considerations |
| Retired person | Health insurance continuity; term insurance need may reduce depending on circumstances |
Young professionals jo apni investments ko gradually increase karna chahte hain, unke liye Step-Up SIP Calculator useful ho sakta hai — protection planning ke baad. Retirement planning ke liye Retirement Corpus Calculator bhi dekh sakte hain.
Riders — Briefly Explained
Riders optional add-ons hote hain jo base policy ke saath liye ja sakte hain — jaise accidental death benefit, critical illness rider, ya waiver of premium. Har rider genuinely necessary nahi hota; inke apne terms, additional cost aur exclusions hote hain. Rider lene se pehle apni actual need evaluate karein — ye ek zaroori step hai jo har insurance for beginners ko follow karna chahiye.
Term Insurance + Return of Premium (ROP)
Kuch term insurance variants mein “Return of Premium” (ROP) feature hota hai, jisme survival ke case mein paid premiums wapas milte hain. In products ko evaluate karte waqt samajhna zaroori hai: aap kya pay kar rahe hain, kya receive karenge, aur actually aapko kya protection chahiye. ROP “hamesha bad” ya “hamesha better” nahi hota — ye suitability aur product ko poori tarah samajhne par depend karta hai, pure term plans ke comparison mein.
Final Insurance Buying Checklist
Before Buying Term Insurance
- Dependents identified
- Financial responsibilities considered
- Adequate cover considered
- Policy term considered
- Medical information disclosed accurately
- Nominee updated
- Policy wording read
- Premium affordability checked
Before Buying Health Insurance
- Sum insured evaluated
- Network hospitals checked
- Waiting periods understood
- Exclusions checked
- Co-payment/deductibles understood
- Sub-limits checked
- Pre-existing disease terms understood
- Claim process understood
- Policy wording reviewed
Insurance for Beginners: The Minimum Insurance Check
- Step 1: Check karein ki aapke paas adequate health coverage hai ya nahi.
- Step 2: Poochein — kya koi financially aapki income par depend karta hai?
- Step 3: Agar haan, appropriate term insurance evaluate karein.
- Step 4: Apna employer-provided coverage review karein.
- Step 5: Nayi policy lene se pehle existing policies review karein.
- Step 6: Policy documents aur nominee details updated rakhein.
Ye general educational steps hain, personalized financial advice nahi.
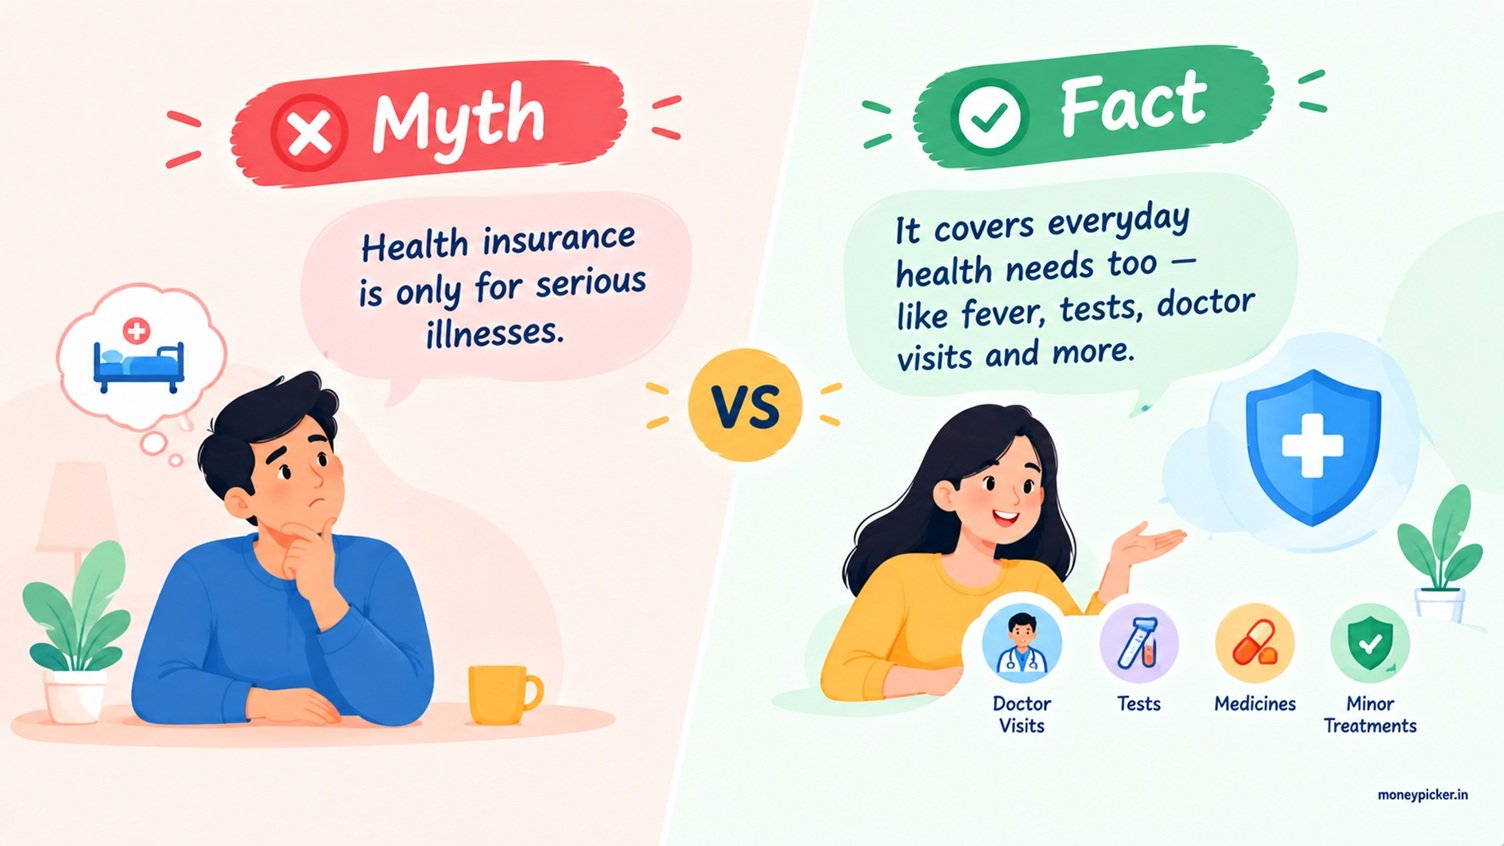
Insurance Myths vs Reality
In myths ko clear karna kisi bhi insurance for beginners guide ka zaroori hissa hai:
Myth: “Insurance sirf old people ke liye hai.”
Reality: Insurance ki need risk exposure aur financial responsibilities par depend karti hai, sirf age par nahi.
Myth: “Employer health insurance hai to mujhe kuch aur sochne ki zaroorat nahi.”
Reality: Employer coverage ko actual needs aur employment circumstances ke basis par evaluate karna chahiye.
Myth: “Cheapest premium matlab best policy.”
Reality: Coverage, exclusions, terms aur suitability bhi equally important hain.
Myth: “Insurance ek investment hai.”
Reality: Insurance primarily risk protection ke liye hai, jabki investments wealth creation ke liye.
Myth: “Emergency fund hai to insurance ki zaroorat nahi.”
Reality: Ye dono alag financial problems solve karte hain.
Frequently Asked Questions (FAQs)
Insurance kya hota hai?
Insurance ek financial arrangement hai jisme premium ke badle insurer specified risk hone par ek defined amount pay karta hai, policy terms ke according. Ye basic concept samajhna kisi bhi insurance for beginners guide ka starting point hota hai.
Term insurance kya hai?
Ye ek pure life insurance product hai jo fixed policy term ke liye death cover deta hai; death hone par nominee ko sum assured milta hai.
Health insurance kya hai?
Ye ek policy hai jo hospitalisation aur medical expenses ko, policy terms ke according, cover karti hai.
Term insurance aur health insurance mein kya difference hai?
Term insurance death ke case mein nominee ko payout deta hai, jabki health insurance hospitalisation/medical expenses cover karta hai. Dono alag risks address karte hain.
Kaunsa insurance zaroori hai?
Ye depend karta hai aapke dependents, liabilities aur lifestyle par. Health insurance almost sabke liye relevant hota hai; term insurance especially un logon ke liye jinke dependents hain.
Kya term insurance sabke liye zaroori hai?
Nahi, ye situation-dependent hai — mainly un logon ke liye relevant hai jinke financial dependents ya liabilities hain.
Health insurance lene se pehle kya check karein?
Sum insured, network hospitals, waiting periods, exclusions, room-rent limits, co-payment, deductibles, sub-limits aur claim process.
Kya employer health insurance enough ho sakta hai?
Ye depend karta hai coverage limits aur family needs par. Isse evaluate karna zaroori hai, sirf assume nahi karna.
Insurance aur investment mein kya difference hai?
Insurance risk protection ke liye hai, investment wealth creation ke liye — dono ka purpose alag hai.
Insurance policy kharidne se pehle sabse important cheezein kya check karein?
Coverage, exclusions, waiting periods, premium affordability aur policy wording — sirf premium amount dekh kar decide na karein.
Umeed hai ye insurance for beginners guide aapko term aur health insurance ke basics clearly samajhne mein madad karega, taaki aap ek informed decision le sakein.
Sources & References
- IRDAI (Insurance Regulatory and Development Authority of India) — regulator for insurance in India
- Income Tax Department, Government of India — for current tax-related rules, where applicable
- Council for Insurance Ombudsmen — grievance redressal for insurance-related disputes