Loans & EMI for Beginners: Loan Kya Hai, Good vs Bad Debt & EMI Explained
EMI dekh kar “bas itna hi toh hai” mat sochiye — asli calculation, asli cost, aur asli risk samjhiye, loan lene se pehle.
Loans & EMI for beginners ka sabse bada confusion yeh hota hai — jab bank ya app kehta hai “sirf ₹20,000 EMI”, toh humein lagta hai loan sasta hai. Lekin us ₹20,000 ke peeche total repayment, interest, aur tenure ka poora hisaab chhupa hota hai, jo agar samjha na jaye toh budget aur savings dono pe pressure daal sakta hai.
Is guide mein hum step-by-step samjhenge — loan kya hai, EMI kya hoti hai, EMI kaise calculate hoti hai, good debt vs bad debt ka fark, EMI-to-income ratio, credit score ka role, aur loan lene se pehle kaunsi cheezein zaroor check karni chahiye. Yeh article kisi bhi specific bank ya loan product ki recommendation nahi hai — sirf ek clear, honest, beginner-friendly explanation hai.
Agar aap apni overall financial journey abhi shuru kar rahe hain, toh loans ko samajhna utna hi zaroori hai jitna investing basics — kyunki debt management bhi financial planning ka ek core part hai.
Loans & EMI for Beginners: Loan Kya Hai?
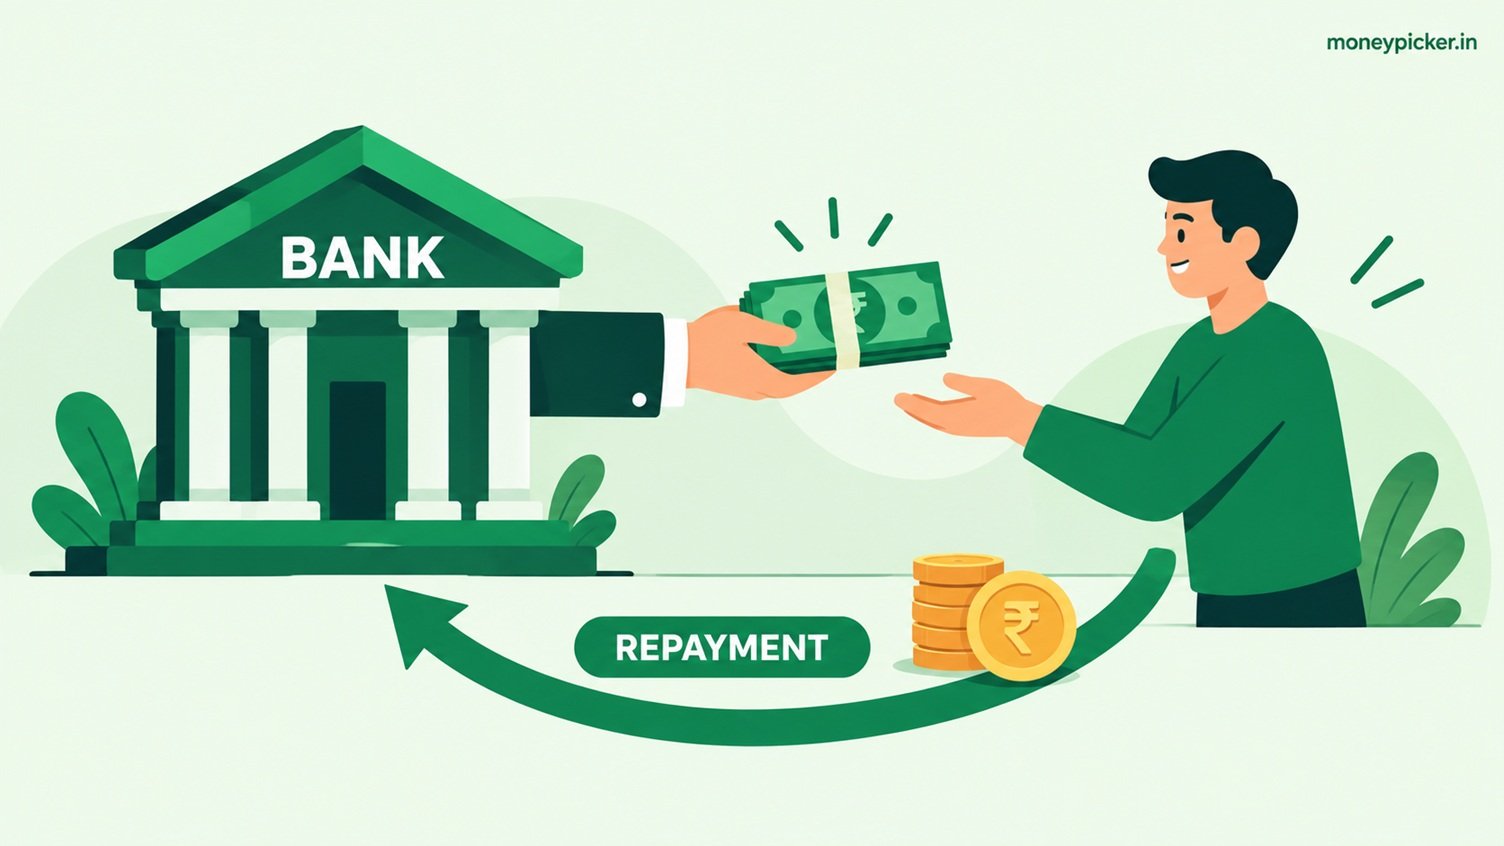
Loan kya hai — simple bhasha mein, loan ek aisi arrangement hai jisme lender (bank ya NBFC) aapko ek fixed amount (principal) deta hai, aur badle mein aap use ek tay time period (tenure) ke andar, interest ke saath wapas karte hain. Yeh repayment monthly instalments mein hoti hai, jise EMI (Equated Monthly Instalment) kehte hain.
Loan amount = ₹5,00,000 | Interest rate = 10% p.a. (reducing balance) | Tenure = 5 years (60 months)
EMI ≈ ₹10,624/month | Total repayment ≈ ₹6,37,440 | Total interest ≈ ₹1,37,440
Yeh sirf ek illustrative calculation hai — actual EMI aapke lender, credit profile aur applicable rate par depend karegi.
EMI Kya Hoti Hai?
EMI kya hoti hai — yeh woh fixed monthly amount hai jo aap loan repay karne ke liye har mahine pay karte hain. Loans & EMI for Beginners guide ka yeh sabse core concept hai. Har EMI do parts mein bat jaati hai:
Loans & EMI for Beginners: EMI Ka Structure
Example: shuru ke EMI mein interest ka hissa zyada hota hai (jaisa upar chart mein dikhaya gaya hai); jaise-jaise principal reduce hota hai, interest ka hissa kam hota jaata hai — lekin total EMI fixed rehti hai.
Teen cheezein EMI ko directly affect karti hain:
- Loan amount — jitna zyada principal, utni zyada EMI
- Interest rate — jitni zyada rate, utni zyada EMI
- Tenure — jitni lambi tenure, utni kam EMI (lekin total interest zyada — isko hum aage detail mein dekhenge)
EMI Kaise Calculate Hoti Hai?
Standard reducing-balance EMI formula yeh hai:
EMI = P × r × (1+r)n ÷ [(1+r)n − 1]
P = Principal (loan amount) | r = monthly interest rate (annual rate ÷ 12 ÷ 100) | n = number of monthly instalments (tenure in months)
Formula thoda intimidating lag sakta hai, lekin idea simple hai: aapka lender calculate karta hai ki har mahine kitna fixed amount pay karne se, poora principal + interest, poori tenure mein cover ho jaaye.
Worked Example
Maan lijiye aap ₹5,00,000 ka loan lete hain, 10% annual interest rate par, 5 saal (60 months) ke liye.
- P = ₹5,00,000
- r = 10 ÷ 12 ÷ 100 = 0.008333 (monthly rate)
- n = 60 months
Formula lagane par: EMI ≈ ₹10,624/month, total repayment ≈ ₹6,37,440, aur total interest ≈ ₹1,37,440.
Yeh calculation manually karna time-consuming hai. Aap MoneyPicker ka free EMI Calculator use kar sakte hain — bas loan amount, interest rate aur tenure daaliye, aur turant EMI, total interest, aur total repayment dekh lijiye.
Loan Interest Kaise Kaam Karta Hai?
Zyadatar loans (home loan, personal loan, car loan) reducing balance method par kaam karte hain — matlab interest sirf outstanding (bacha hua) principal par calculate hota hai, poore original loan amount par nahi.
Isi wajah se:
- Shuru ke EMIs mein interest ka hissa zyada hota hai (kyunki outstanding principal high hota hai)
- Baad ke EMIs mein principal ka hissa zyada hota hai (kyunki outstanding principal kam ho chuka hota hai)
- Longer tenure normally zyada total interest deti hai, kyunki principal zyada mahino tak outstanding rehta hai
| Year | Approx. Interest Portion | Approx. Principal Portion |
|---|---|---|
| Year 1 | Zyada | Kam |
| Year 3 (mid-tenure) | Moderate | Moderate |
| Final Year | Kam | Zyada |
Lower EMI ka matlab hamesha cheaper loan nahi hota. Lambi tenure EMI ko chhota dikhati hai, lekin total interest cost badha deti hai. Hamesha EMI aur total repayment dono dekhein.
Flat Rate vs Reducing Balance Interest
Kuch lenders/products “flat rate” bhi advertise karte hain, jo reducing balance se different hota hai.
Flat Interest Rate
Interest poore original principal par calculate hota hai, poori tenure ke liye — chahe aapne kितna bhi repay kar diya ho. Isse effective cost, quoted rate se kaafi zyada ho sakti hai.
Reducing Balance Rate
Interest sirf outstanding principal par calculate hota hai. Zyadatar home loans, personal loans is method ko follow karte hain, aur yeh generally borrower ke liye zyada transparent hota hai.
Do loans jinki “quoted rate” similar lage, unki effective cost bahut different ho sakti hai agar ek flat rate use kare aur dusra reducing balance. Isliye kabhi bhi sirf headline rate compare mat kijiye — apne loan agreement ya Key Facts Statement (KFS) mein calculation method zaroor verify kijiye.
Good Debt vs Bad Debt — Difference Kya Hai?
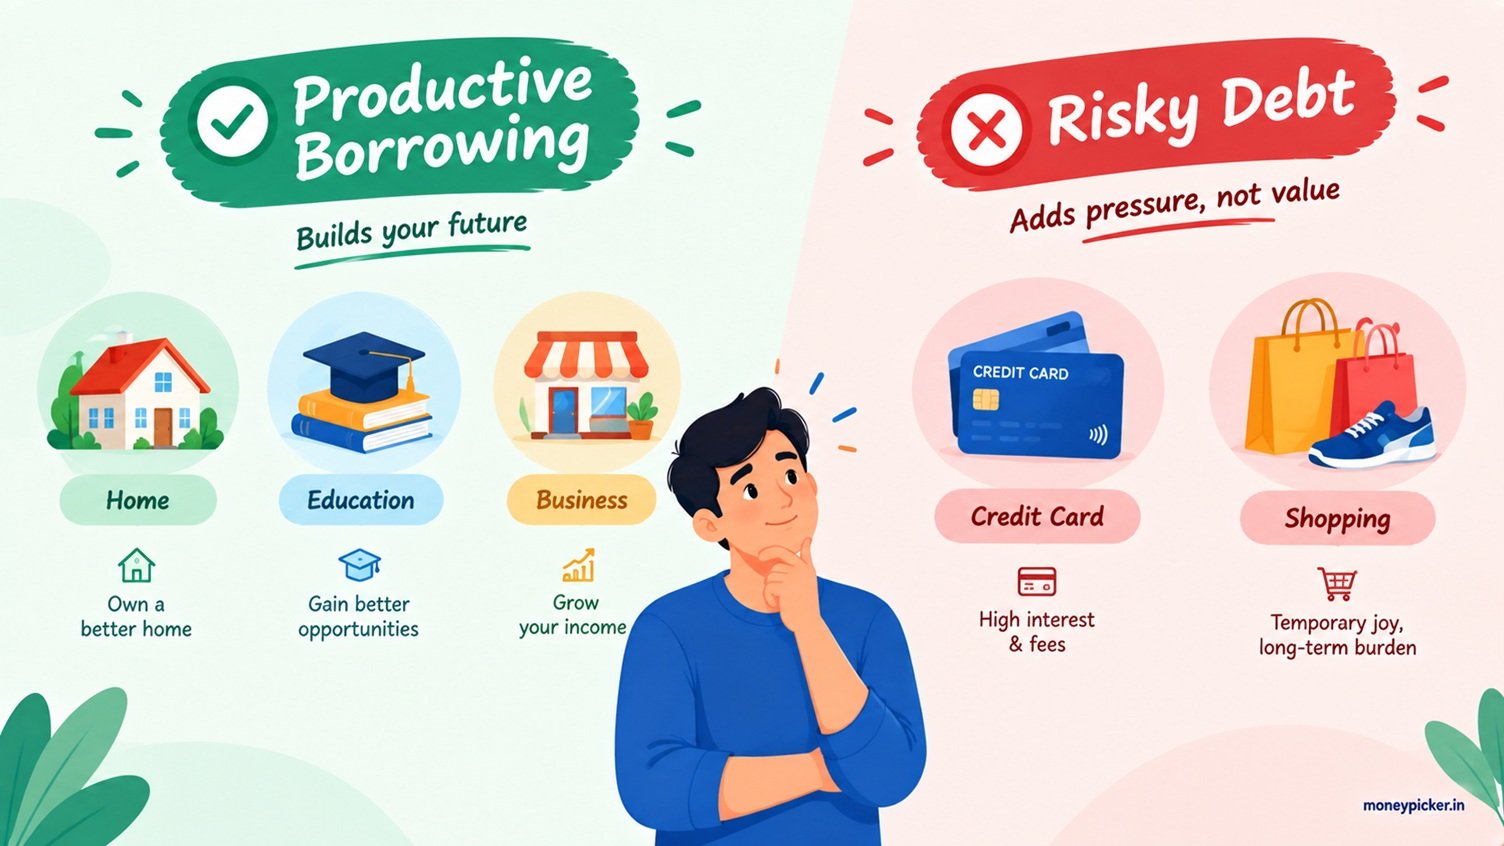
“Good debt” aur “bad debt” koi absolute labels nahi hain — yeh depend karta hai purpose, cost, affordability aur expected benefit par. Loans & EMI for Beginners samajhne ke liye yeh farak jaanna zaroori hai — same loan type kisi ke liye reasonable ho sakta hai, aur kisi doosre ke liye risky.
Strategic Borrowing
- Home loan — agar affordable EMI aur stable income ho
- Education loan — agar course aur career outcome cost justify kare
- Business loan — agar business economics repayment support karein
Expensive / Consumption Debt
- High-interest credit card revolving debt
- Lifestyle consumption ke liye expensive personal loans
- Unnecessary discretionary spending ke liye borrowing
- Purani EMI chukane ke liye naya loan lena
Har home loan “good” nahi hota, aur har personal loan “bad” nahi hota. Evaluate kijiye: purpose, cost of borrowing, EMI burden, tenure, aur income disruption ka risk — tab decide kijiye.
Types of Loans — Beginner Guide
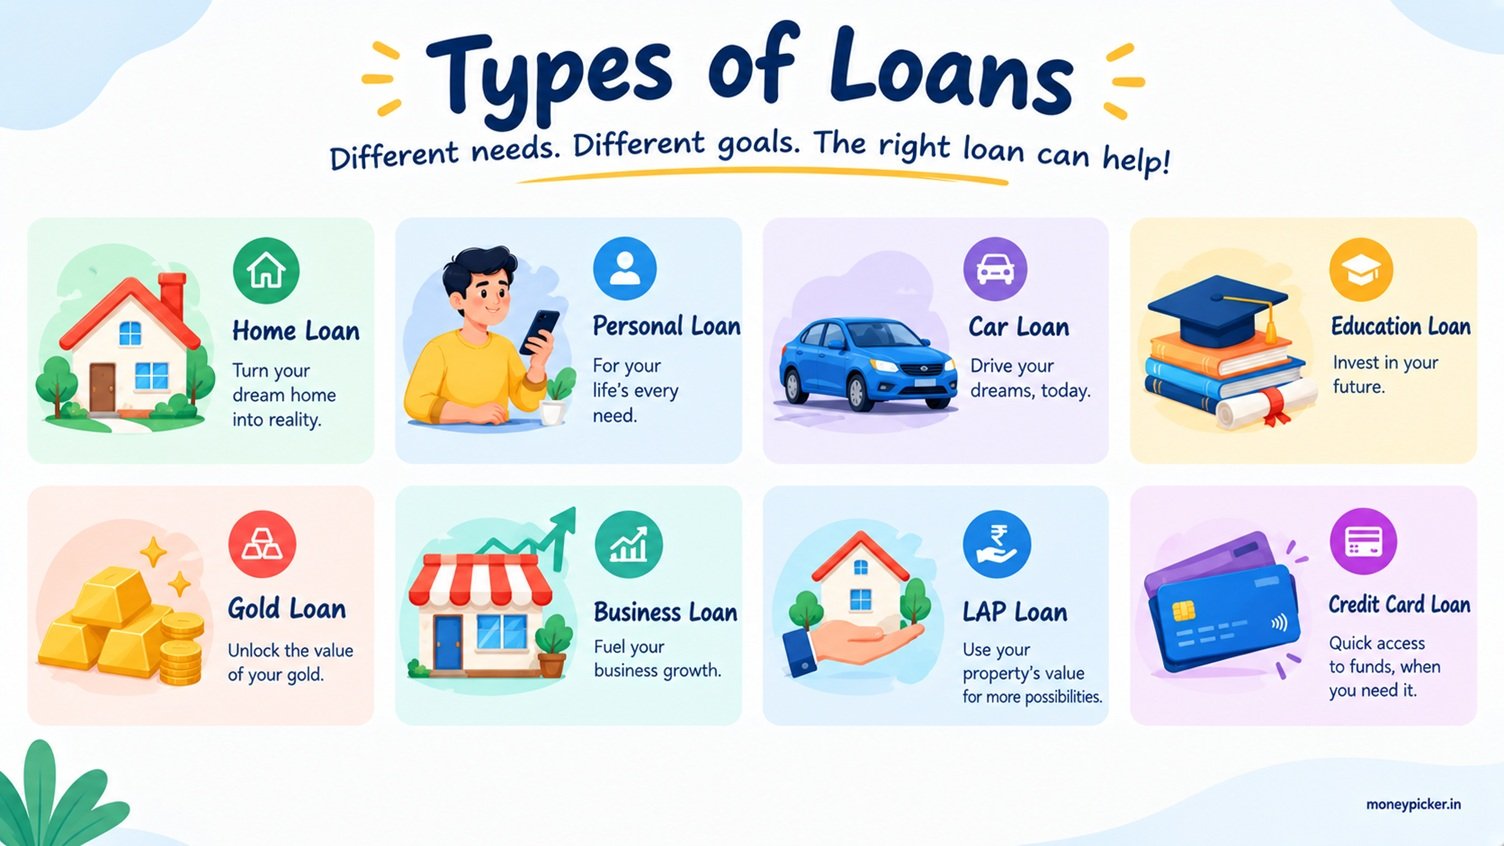
Koi bhi Loans & EMI for Beginners guide types of loans samjhaye bina complete nahi hoti. Neeche common loan types aur unke saath kya dekhna chahiye, yeh diya gaya hai:
| Loan Type | Common Purpose | Beginners Kya Dekhein |
|---|---|---|
| Home Loan | Ghar kharidna/banana | Long tenure, large EMI-to-income impact — affordability carefully check karein |
| Personal Loan | Flexible/urgent needs | Generally higher interest rate, unsecured — purpose justify karna important |
| Car Loan | Vehicle purchase | Depreciating asset — loan amount aur tenure zyada lamba na kariye |
| Education Loan | Higher studies | Course ka expected ROI aur moratorium terms check karein |
| Gold Loan | Short-term liquidity | Gold collateral hota hai — default hone par gold loss ka risk |
| Business Loan | Working capital/expansion | Business cash flow repayment support karta hai ya nahi, yeh evaluate karein |
| Loan Against Property | Large funding needs | Property collateral hoti hai — default ka risk zyada serious |
| Credit Card / Revolving Credit | Short-term spending | Yeh traditional EMI loan jaisa nahi hai — unpaid balance par interest bahut high ho sakta hai |
Note: Yahan koi specific interest rate quote nahi ki gayi hai kyunki rates lender, credit profile aur market conditions ke hisaab se change hoti rehti hain. Current rate ke liye apne lender ka official offer/KFS check karein.
Agar loan lene se pehle aap apni overall investing aur saving strategy bhi plan karna chahte hain, toh MoneyPicker ke Tools & Calculators section mein aur bhi free calculators available hain.
EMI-to-Income Ratio Kya Hai?
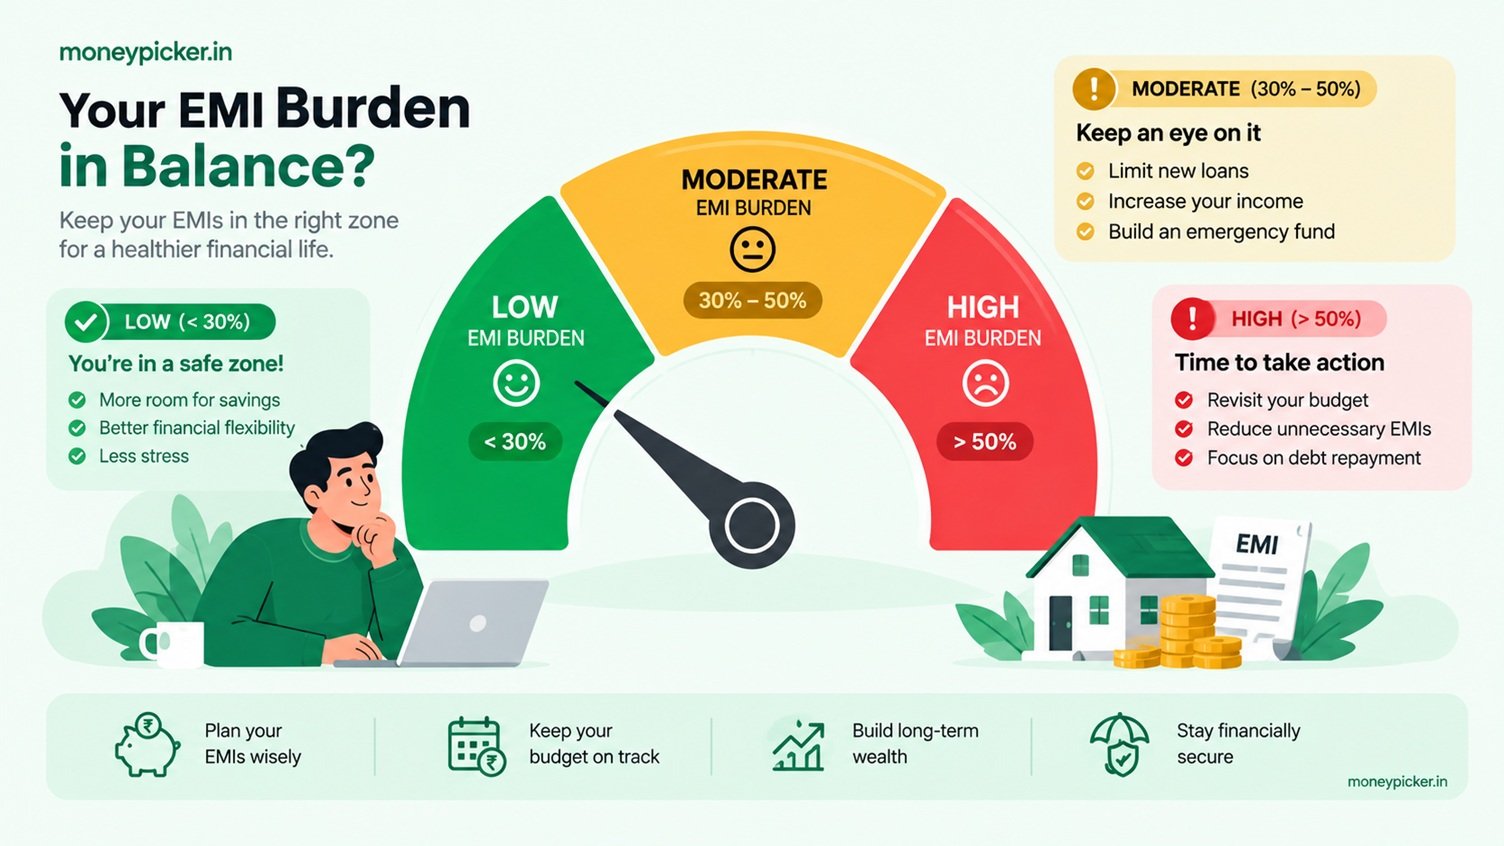
EMI-to-Income Ratio ek simple lekin powerful check hai jo batata hai ki aapki total monthly EMIs, aapki income ka kitna hissa consume kar rahi hain. Loans & EMI for Beginners planning mein yeh sabse practical calculation hai.
EMI-to-Income Ratio = (Total Monthly EMIs ÷ Monthly Take-Home Income) × 100
Example Meter
Take-home income = ₹80,000 | Total EMIs = ₹20,000 | Ratio = 25%
Kuch planners loosely 30-40% jaisa benchmark mention karte hain, lekin yeh sirf ek commonly-used planning guideline hai — koi regulatory rule nahi. Aapki actual affordability depend karti hai: income stability, existing expenses, dependents, emergency fund, other debt, insurance, aur future goals par.
Loan Tenure Ka EMI Aur Interest Par Asar
Loan tenure directly EMI aur total interest dono ko affect karti hai — Loans & EMI for Beginners ka yeh ek aur important concept hai:
Short Tenure
- Higher EMI
- Generally lower total interest
- Loan jaldi close ho jaata hai
Long Tenure
- Lower EMI
- Generally higher total interest
- Debt zyada lambe time tak rehta hai
| Tenure | Approx. EMI | Approx. Total Repayment | Approx. Total Interest |
|---|---|---|---|
| 3 years (36 months) | ₹33,217 | ₹11,95,812 | ₹1,95,812 |
| 5 years (60 months) | ₹22,246 | ₹13,34,760 | ₹3,34,760 |
| 7 years (84 months) | ₹17,655 | ₹14,83,020 | ₹4,83,020 |
(Illustrative example: ₹10,00,000 loan @ 12% p.a. reducing balance, alag-alag tenures ke saath.)
Credit Score / CIBIL — Loan Mein Iska Role
Credit score (jaise CIBIL score) ek numeric summary hai aapki past repayment behaviour ki — jaise loan EMIs aur credit card bills time par pay ki gayi hain ya nahi. Loans & EMI for Beginners ke context mein credit score ka role samajhna zaroori hai. Aap apna score official CIBIL website par check kar sakte hain.
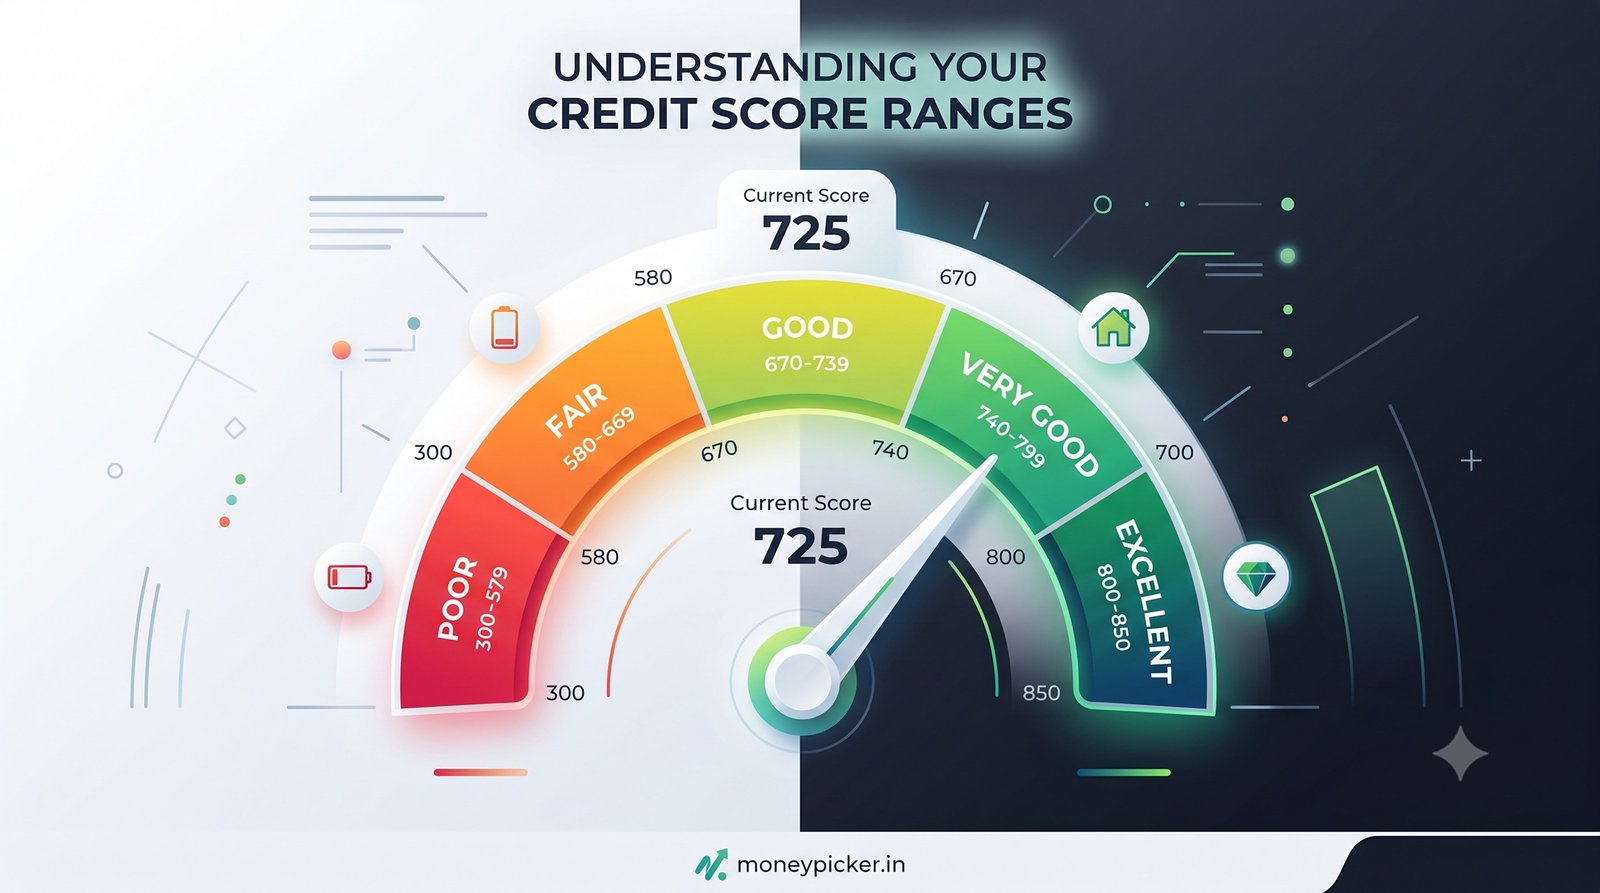
- Lenders is score ko use karte hain risk assess karne ke liye — approval decision aur applicable interest rate dono is se influence ho sakte hain
- Missed EMI ya credit card payments credit history ko negatively impact kar sakte hain
- Short time period mein multiple loan/credit applications karna bhi caution ke saath karna chahiye, kyunki repeated hard inquiries score par asar daal sakti hain
Koi bhi specific credit score loan approval ki guarantee nahi deta. Approval final lender ke internal policies, income, existing debt aur other factors par depend karta hai. Apna score verify karne ke liye official credit bureau resources use karein.
Loan Lene Se Pehle Kaunse Charges Check Karein?
Interest rate ke alawa, loans mein kai aur charges bhi ho sakte hain. Apna loan agreement aur Key Facts Statement (KFS) dhyan se padhein — KFS ke baare mein aur jaanne ke liye RBI ki official website dekhein — aur inhe verify karein:
Interest rate (fixed ya floating)
Effective cost / APR jahan disclosed ho
Processing fee
Documentation charges
Insurance/add-on charges (agar bundled hain)
Late payment charges
Penal charges
Prepayment/foreclosure conditions
Har lender ke charges different ho sakte hain — koi bhi fee assume mat kijiye, apna specific loan agreement/KFS verify kijiye.
Prepayment / Foreclosure — Kab Sochna Chahiye?
Prepayment ka matlab hai loan tenure poora hone se pehle extra amount pay karna, jisse principal jaldi reduce ho. Foreclosure ka matlab hai poora outstanding loan ek saath close kar dena. Loans & EMI for Beginners journey mein yeh decision samajhdaari se lena chahiye.
- Prepayment tab useful ho sakta hai jab aapke paas surplus funds hon aur emergency fund already secure ho
- Apna emergency fund destroy karke loan close mat kijiye — unexpected situations ke liye buffer zaroori hai
- Agar aapke paas multiple debts hain, toh generally sabse high-cost debt (jaise credit card) ko priority dena zyada beneficial ho sakta hai
- Prepayment/foreclosure se pehle applicable charges aur conditions apne loan agreement mein zaroor verify karein
“Hamesha loan prepay kariye” jaisi advice universally sahi nahi hoti. Yeh depend karta hai aapki liquidity, other debt, aur applicable prepayment charges par.
Loans & EMI for Beginners: Real-Life Example
Maan lijiye Rohan ₹75,000/month kamaate hain aur ₹10,00,000 ka personal loan consider kar rahe hain, 12% p.a. (illustrative rate), 5 saal ke liye.
| Metric | Approx. Value |
|---|---|
| Monthly EMI | ₹22,246 |
| Total Repayment | ₹13,34,760 |
| Total Interest | ₹3,34,760 |
| EMI-to-Income Ratio | ≈ 29.7% |
Agar Rohan tenure 7 saal kar dein, EMI ghatkar approx ₹17,655 ho jaayegi, lekin total interest badhkar approx ₹4,83,020 ho jaayega. Yahan ek trade-off hai — monthly cashflow relief vs long-term cost.
Illustrative example hai, personalized advice nahi. Rohan ko apni existing EMIs, emergency fund, aur job stability bhi consider karni chahiye before deciding.
Loans & EMI for Beginners: 10 Common Mistakes
Neeche diye gaye Loans & EMI for Beginners mistakes list beginners ko sabse zyada financially nuksaan pahunchati hai:
Sirf EMI dekhna, total repayment ignore karna
Interest rate ko akela compare karna, method (flat/reducing) ignore karna
Long tenure ko automatically “better” samajhna
Processing fee/other charges ignore karna
Emergency fund ke bina loan lena
Credit card debt ko ignore karke naye loans lena
Short time mein multiple loans simultaneously lena
Prepayment conditions na padhna
Income uncertainty ko underestimate karna
Loan amount maximum eligible tak le lena
Loan Afford Kar Sakte Hain? Ek Practical Checklist
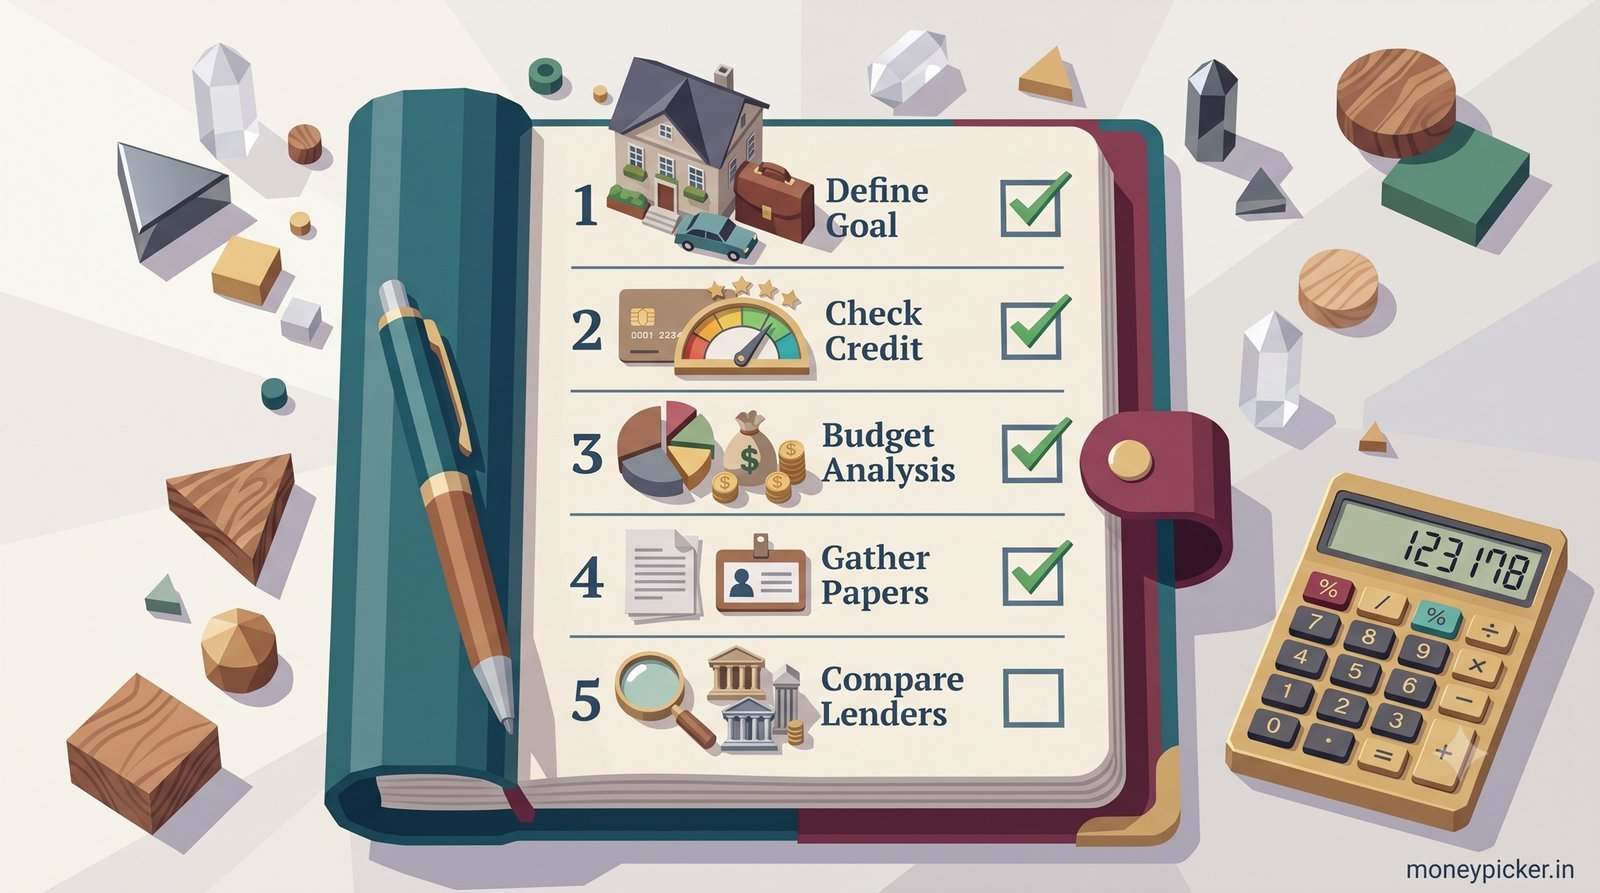
Yeh Loans & EMI for Beginners checklist final decision lene se pehle zaroor use karein:
- EMI kitni hogi?
- Total repayment aur total interest kitna hoga?
- EMI income ka kitna percentage consume karegi?
- Kya emergency fund already ready hai?
- Income stable hai ya variable?
- Existing EMIs kitni hain?
- Credit card dues outstanding toh nahi hain?
- Loan ka purpose clearly justified hai?
- Kya cheaper borrowing option available hai?
- Kya EMI ke saath investing/saving continue kar paayenge?
- Agar income temporarily drop ho jaaye, toh kya hoga?
Related MoneyPicker Tools
Apni Loans & EMI for Beginners journey ko aage badhane ke liye, yeh free tools use karein:
Loan amount, rate aur tenure daaliye — instantly EMI, total interest aur total repayment dekhiye.
Loans ke alawa, agar aap apni money journey ko poori tarah samajhna chahte hain, toh yeh guides bhi helpful ho sakti hain:
- Start Here — beginners ke liye step-by-step guided flow
- Investing for Beginners — apni savings ko grow karna seekhein
- Tools & Calculators — SIP, brokerage aur position-size calculators
Aap MoneyPicker.in par aur bhi free financial tools aur beginner guides explore kar sakte hain — investing, trading aur financial planning se related.
Frequently Asked Questions (FAQs)
Loan kya hai?
Loan ek arrangement hai jisme lender aapko ek fixed amount deta hai, jise aap interest ke saath, ek tay tenure ke andar EMI ke through wapas karte hain.
EMI kya hoti hai?
EMI (Equated Monthly Instalment) fixed monthly amount hai jo loan repay karne ke liye pay kiya jaata hai — ismein principal aur interest dono shamil hote hain.
EMI kaise calculate hoti hai?
EMI = P × r × (1+r)^n ÷ [(1+r)^n − 1], jahan P principal hai, r monthly interest rate hai, aur n total number of monthly instalments hai. Aap MoneyPicker ka EMI Calculator bhi use kar sakte hain.
Good debt vs bad debt kya hai?
Yeh koi fixed category nahi hai — depend karta hai purpose, cost, affordability aur expected benefit par. Same loan type kisi ke liye reasonable ho sakta hai, aur kisi doosre ke liye risky.
EMI-to-income ratio kya hota hai?
Yeh ratio batata hai ki aapki total monthly EMIs, aapki take-home income ka kitna % consume kar rahi hain. Formula: (Total EMIs ÷ Income) × 100.
Long tenure loan lena better hai?
Long tenure EMI ko kam karti hai, lekin generally total interest badha deti hai. “Better” option aapki cashflow needs aur long-term cost tolerance par depend karta hai.
Personal loan aur home loan mein kya difference hai?
Home loan typically secured hota hai (property collateral ke saath) aur longer tenure ka hota hai; personal loan generally unsecured hota hai, shorter tenure ka, aur purpose flexible hota hai.
Loan lene se credit score improve hota hai?
Time par consistent repayment credit history ko positively reflect kar sakti hai, lekin sirf loan lena guarantee nahi deta ki score improve hi hoga — yeh overall repayment behaviour par depend karta hai.
Loan prepayment kya hota hai?
Prepayment ka matlab hai tenure poora hone se pehle extra amount ya poora outstanding loan pay kar dena, jisse interest cost kam ho sakti hai — applicable charges verify karne ke baad.
Loan lene se pehle kya check karna chahiye?
EMI, total repayment, interest rate/method, processing aur other charges, prepayment conditions, aur apni EMI-to-income affordability zaroor check karein.
Kya lower EMI ka matlab cheaper loan hota hai?
Nahi, hamesha nahi. Lower EMI aksar longer tenure se aata hai, jo total interest cost ko badha deta hai. Total repayment compare karna zyada accurate hai.
Credit card debt ko loan se consolidate karna chahiye?
Yeh depend karta hai naye loan ki cost aur terms par. High-interest credit card debt ko lower-cost option se consolidate karna kabhi-kabhi beneficial ho sakta hai, lekin decision case-by-case evaluate karna chahiye.
Sources & References
- Reserve Bank of India (RBI) — banking regulations, Key Facts Statement guidelines
- TransUnion CIBIL — credit score and credit report information
- SEBI — for broader investor education context
Loans & EMI for Beginners ko samajhna ek one-time exercise nahi hai — jab bhi aap koi naya loan consider karein, in concepts ko dobara revisit kijiye aur apni current financial situation ke hisaab se decide kijiye.